Home › Equity release › Calculator
Lender criteria published July 2026; reviewed September 2026Equity Release Calculator
If you're looking for an equity release calculator that gives you a straight figure, you're in the right place. Mine asks for two things, your age and a rough property value, and nothing else: no name, no phone number, no email. The bands behind it are the same lender criteria I use when I produce a written quotation.
- Member of the Equity Release Council
- SOLLA Later Life Lending Advice Standard
- Authorised and regulated by the FCA, FRN 981845
Two questions. No name, phone number or email.
- You must be 55 or over and own your home in the UK
- You keep 100% ownership and stay in your home for life
- No monthly repayments unless you choose to make them
- No negative equity guarantee: you'll never owe more than your home is worth
- Nothing you type here is sent anywhere
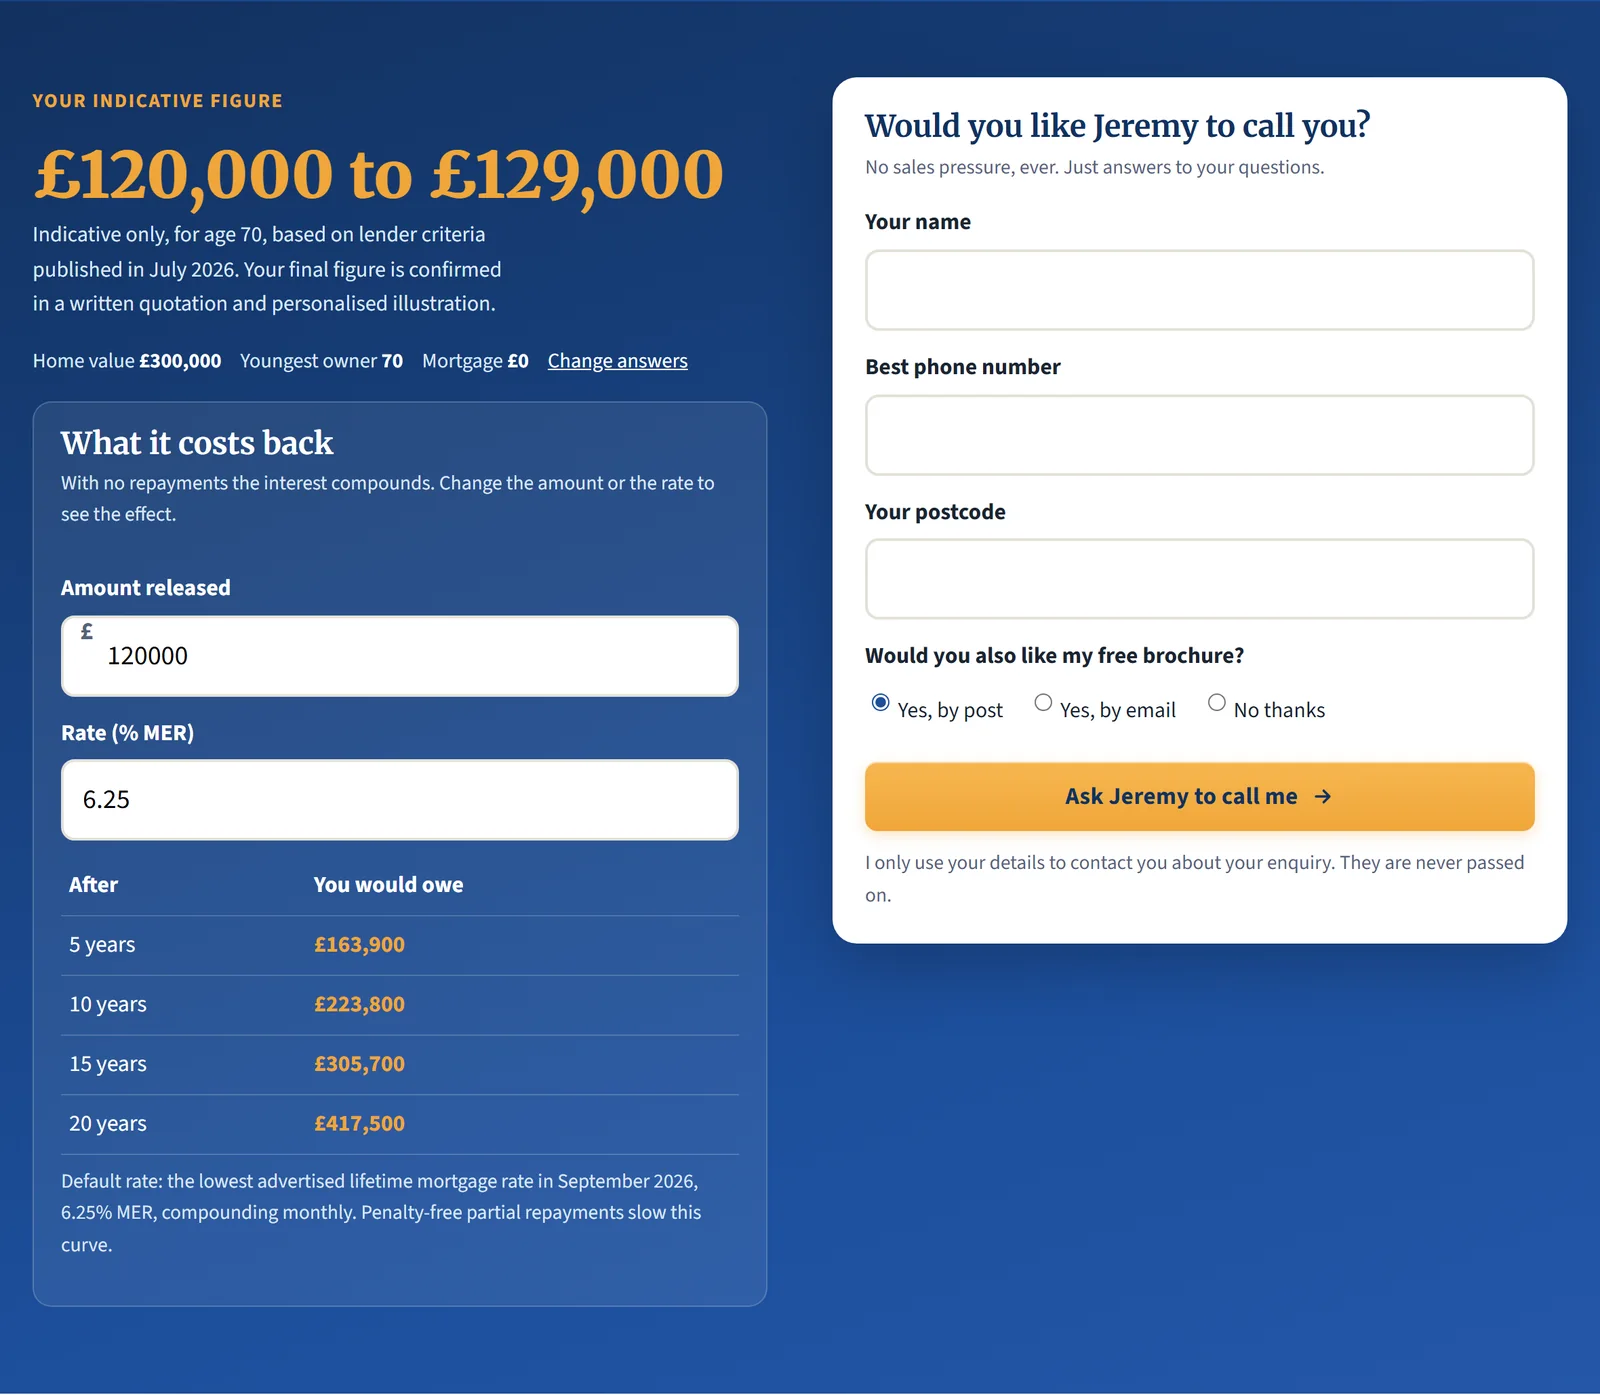
What it costs back
With no repayments the interest compounds. Change the amount or the rate to see the effect.
| After | You would owe |
|---|
Default rate: the lowest advertised lifetime mortgage rate in September 2026, 6.25% MER, compounding monthly. Penalty-free partial repayments slow this curve.
Thank you. Jeremy will be in touch shortly.
If you'd rather not wait, call 07768 972861.
Quick answer: how much equity can you release?
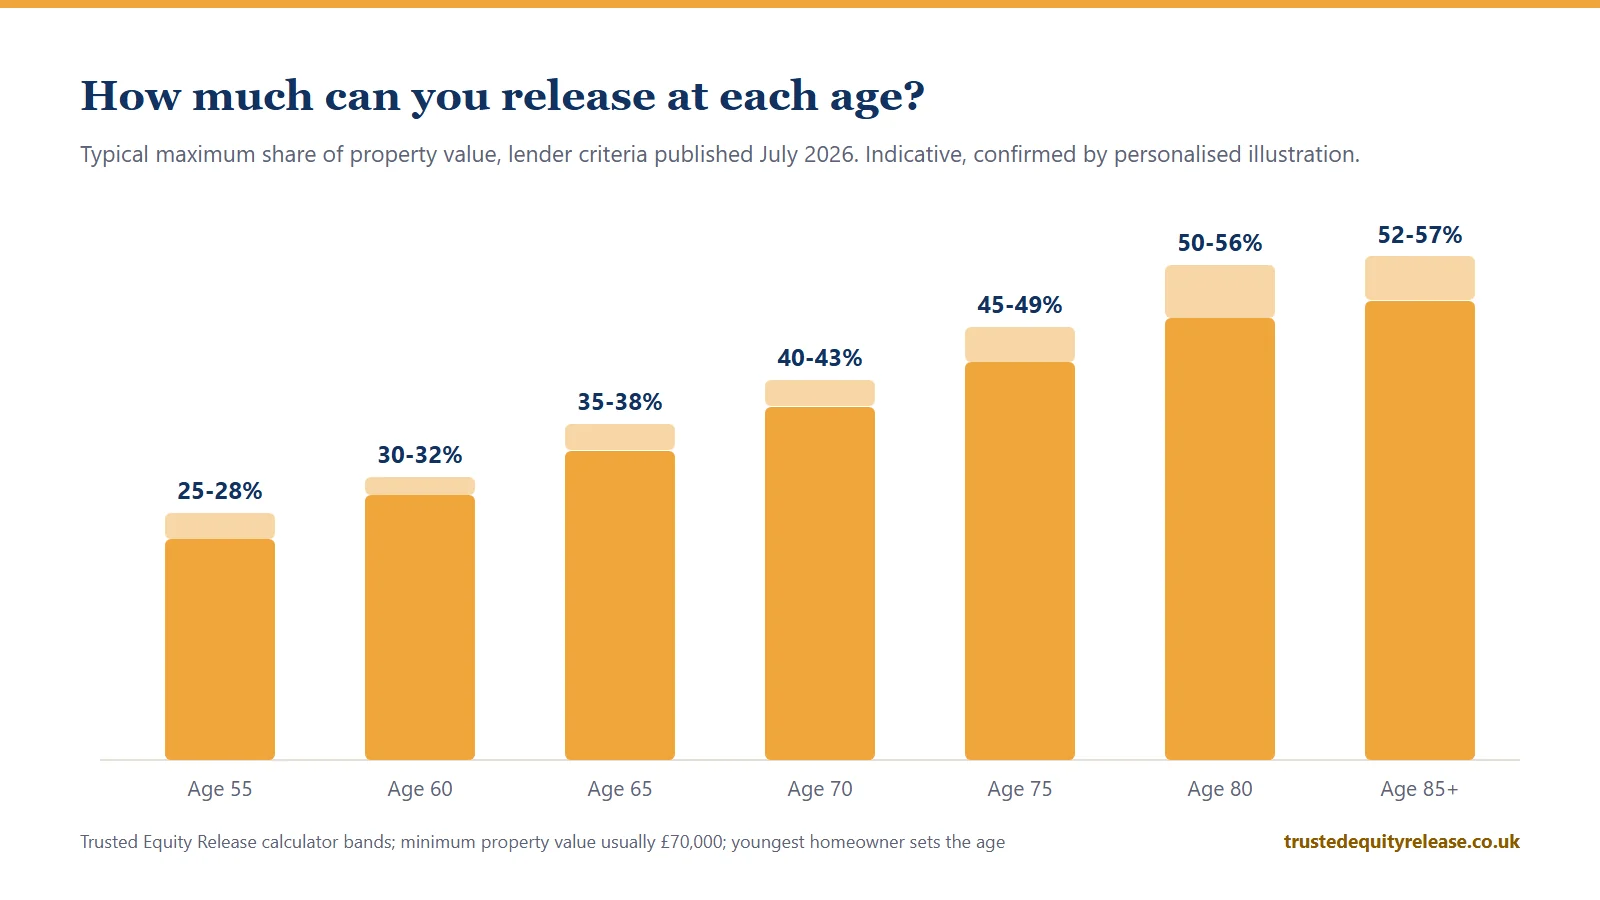
Most people can release between 25% and 57% of their home's value. The typical maximum is 25% to 28% at 55, 40% to 43% at 70, and 50% to 57% from 80. Age and property value set the range.
Why speak to us if you are considering equity release?
The calculator gives you an estimate; I give you the real number. Everything on this page is an estimation built from published lender criteria, and accurate figures are available on request once I know a little more about you and your property. I am a whole-of-market adviser, a member of the Equity Release Council, and I have specialised in later-life lending since 2009. Trusted Equity Release is a trading name of Pellucid Ltd, authorised and regulated by the Financial Conduct Authority, FRN 981845.
The barrier here is low, deliberately. Speaking to me for an opinion, or a second opinion on a quote you already have, costs you nothing, and I would genuinely rather you asked. Email me, request a printed brochure, or get in touch on the number at the top of this page.
On the calculator itself: nothing is collected and nothing follows you around afterwards. Plenty of equity release calculators are contact forms with a number attached, and I did not want one.
How much can you release at each age?
The table the calculator works from, based on lender criteria published in July 2026, rounded down:
| Age of youngest homeowner | Typical maximum release |
|---|---|
| 55 | 25% to 28% of property value |
| 60 | 30% to 32% |
| 65 | 35% to 38% |
| 70 | 40% to 43% |
| 75 | 45% to 49% |
| 80 | 50% to 56% |
| 85 and over | 52% to 57% |
Age is banded on the youngest owner because the plan runs until the last of you dies or moves into long-term care. Minimum property value is usually £70,000. These are maximums: in practice people take far less. FCA data across 2022 to 2025 shows the median lifetime mortgage at around 15% loan-to-value, against a median borrower age of about 71.
How do you calculate equity release yourself?
Multiply your property value by the percentage for your age, then subtract any existing mortgage, because that must be repaid from the release first. A 70-year-old in a £300,000 house: 40% to 43% gives £120,000 to £129,000. With £40,000 left on the mortgage, the cash available becomes £80,000 to £89,000.
What will the amount you release cost back?
At September 2026's lowest advertised rate of 6.25% MER, a £60,000 release with no repayments becomes about £111,900 after 10 years, £152,800 after 15 and £208,700 after 20. The interest compounds because nothing is being paid down.
That number is the reason my advice sometimes ends with "not yet". You can slow it with penalty-free partial repayments, which every Equity Release Council plan has allowed since March 2022, or by taking a smaller advance with a drawdown reserve. Current pricing and what moves it are on my equity release interest rates page.
What changes the figure?
Age does the heavy lifting, as the table shows. Three other things move it:
- The property itself. Standard construction in a saleable location gets the full bands. Flats above shops, ex-local-authority blocks and non-standard construction get trimmed offers or a decline.
- Your health. Enhanced plans lend more, or price lower, where health or lifestyle is likely to shorten the plan. It feels uncomfortable to disclose; it is worth doing.
- Lump sum or drawdown. A smaller initial advance with a reserve usually prices better than taking the maximum on day one, and you only pay interest on what you have drawn.
Is the calculator's figure guaranteed?
No, and be wary of any calculator that pretends otherwise. The figure is indicative, based on published lender criteria; your confirmed number arrives in a written quotation and a personalised illustration after financial advice, which is mandatory on every equity release plan under FCA rules and Equity Release Council standards. You continue living in your own home throughout; the loan is repaid when the property is sold, normally on death or a move into long-term care.
The process also respects a change of heart. One client's grandmother paused her application partway through when she had a wobble about it, and finished it months later once she was sure. I sat with her twice. The paperwork waited; that is how it should work.
Before you take any figure further, read the honest side of the ledger too: the debt grows if you make no repayments, exactly as the cost table above shows, and that can affect what your family inherits and any means-tested benefits. Both are covered properly on will my family end up in debt? and can I still leave an inheritance?. Every plan I recommend carries the Council's no negative equity guarantee.
FAQ
How much does a solicitor charge for equity release?
Can you use the calculator if you are under 55?
Does getting a figure commit you to anything?
Sources
- Lender criteria published July 2026 (the calculator's bands, reviewed at each refresh)
- FCA later life mortgages market study MS26/1.1, Product Sales Data medians
- Equity Release Council standards
- MoneyHelper: equity release
- FCA register: Pellucid Ltd, FRN 981845
Book your free initial consultation today.
Pick up the phone and speak to Jeremy directly. If equity release is not the right choice, I will say so.
07768 972861 Back to the calculator