Can you use equity release to buy another property?
Quick answer: can you release equity to buy a second home?
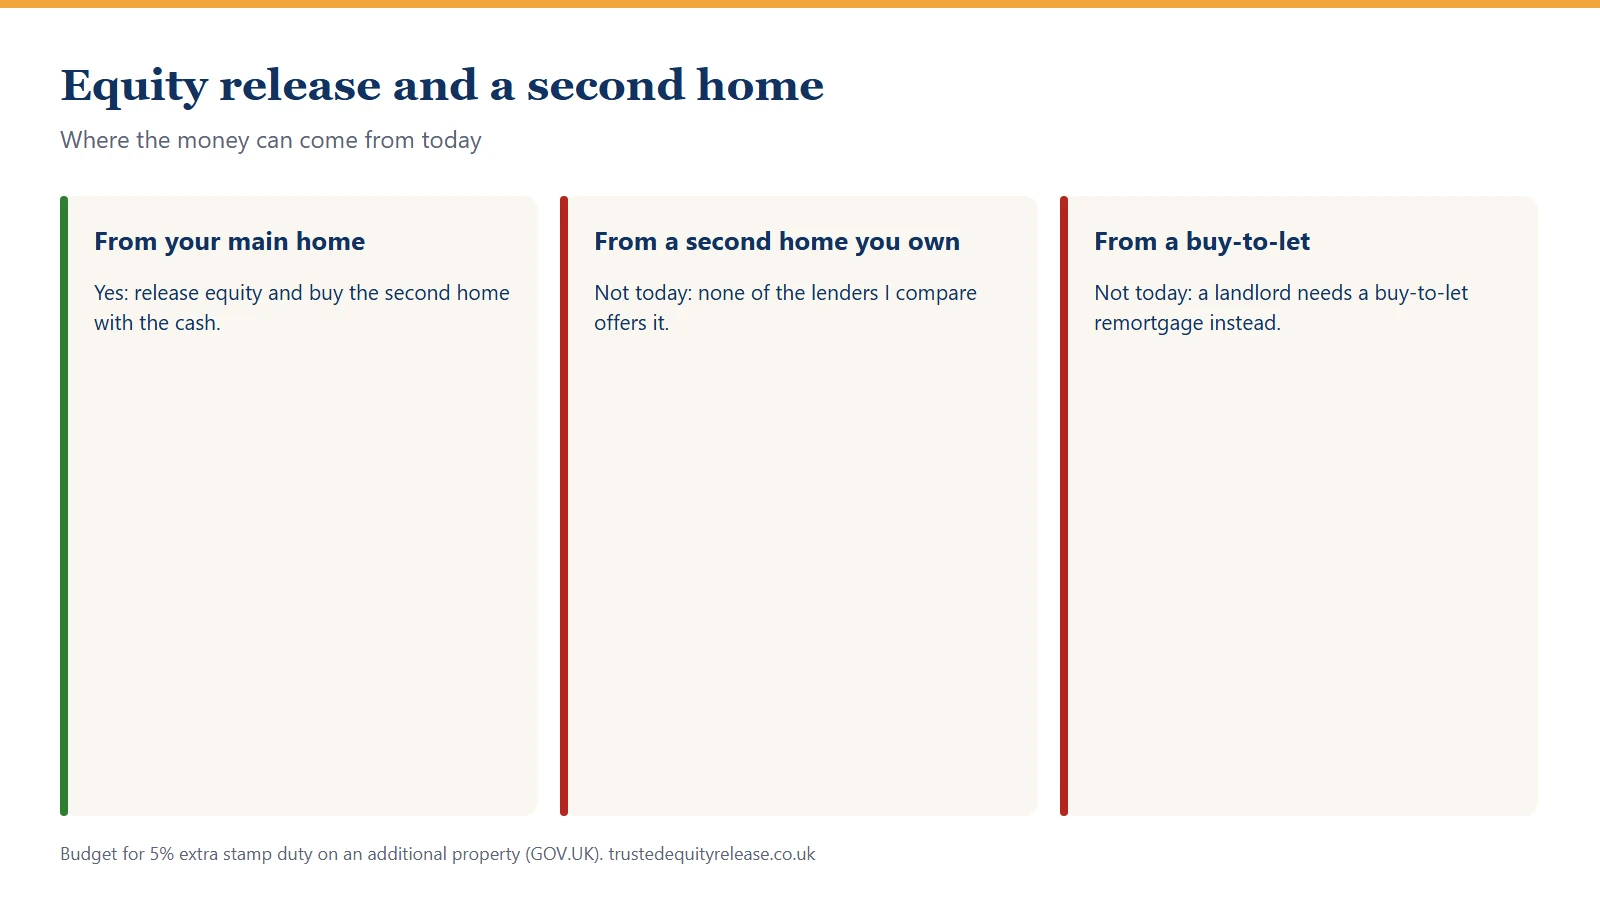
Yes, by releasing it from your main home and buying the second one with the cash. What you can't do at the moment is take equity release on the second home itself, or on a buy-to-let: none of the lenders I compare offers that today.
How much of your equity can you use to buy another property?
All of what you release, because how you spend it is up to you. The limit is what a lender will release from your main home, typically 25% to 28% of its value at 55, 40% to 43% at 70 and 50% to 57% from 80, less any mortgage it has to clear first. The second property then has its own costs: stamp duty with the surcharge on additional homes, and legal fees. The calculator gives an indicative figure for your age.
Moving your plan to a new main home is a different question: see whether you can move house with equity release.
How much could you release for a second home?
As much as your age allows against your main residence, less any mortgage still on it, taken as a lump sum or in stages. The typical maximum is 25% to 28% of the home's value at 55, 40% to 43% at 70 and 50% to 57% from 80, and the calculator gives an indicative figure in three questions.
Budget for the costs of the second property too. GOV.UK says you'll usually pay 5% on top of the normal stamp duty rates when buying a property means you'll own more than one, and that comes out of the money you release. The interest is the bigger cost over time: you'll find this month's rates on my rates page.
Can you release equity from a second home you already own?
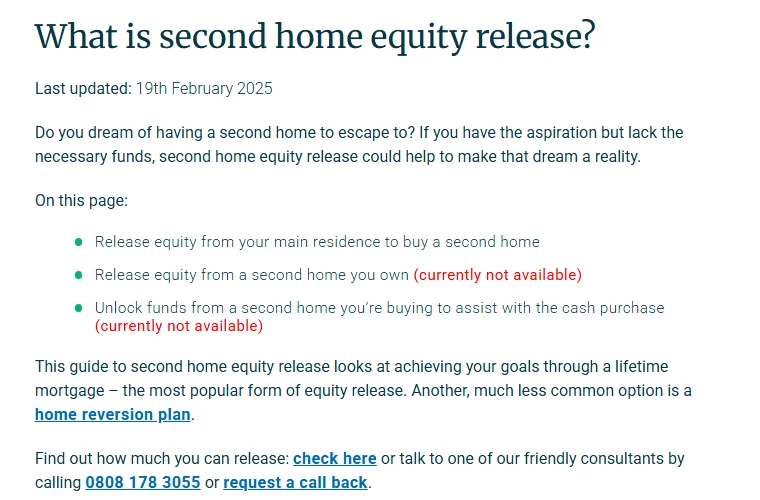
Not at the moment. There used to be lifetime mortgages for holiday homes and second homes, with stricter criteria, and lenders are looking at whether to offer them again, but none of the lenders I compare offers one today. Equity Release Wise's guide lists releasing from a second home you own as currently not available. If that changes, this page will say so.
What about a buy-to-let or rental property?
Releasing equity from a rental property isn't possible with a lifetime mortgage, and you can't take a lifetime mortgage on a property you'll let out. If you're a landlord wanting to raise money from a rental, that's a buy-to-let remortgage, which my colleagues at Pellucid, the same firm, arrange. You can still use money released from your own home to buy a property to let, but the rent is taxable income and the plan's interest keeps rolling up.
Is a remortgage or a retirement interest-only mortgage cheaper?
Often, if your income allows. A retirement interest-only mortgage means paying the interest every month, but the debt stays the same instead of growing, and my page on how a retirement interest-only mortgage works sets out who qualifies. If you're still earning, an ordinary remortgage may cost less again, though clearing an existing deal early can mean early repayment charges.
Why ask me about buying a second home?
Because the order of the steps decides what it costs, and I'll compare every route before recommending one: a lifetime mortgage on your main home, a retirement interest-only mortgage, or a remortgage through my colleagues. I'm whole of market and a member of the Equity Release Council. Trusted Equity Release is a trading name of Pellucid Ltd, authorised and regulated by the Financial Conduct Authority, FRN 981845. Get in touch.
“Amazing support from start to finish. Highly recommend this company. Jan”
Sources
- Equity Release Wise: second home equity release
- GOV.UK: Stamp Duty Land Tax, residential rates
- Trusted Equity Release: equity release calculator
Book your free initial consultation today.
Pick up the phone and speak to Jeremy directly. If equity release is not the right choice, I will say so.
07768 972861 Or try the quick calculator