Quick answer: what happens when you inherit a house with equity release on it?
The plan has to be repaid before the house is yours outright, usually by selling it or by paying off the loan from other money. Tell the lender, get probate, and expect around 12 months to settle. Interest runs until then, but you never owe more than the house sells for.
What should you do first?
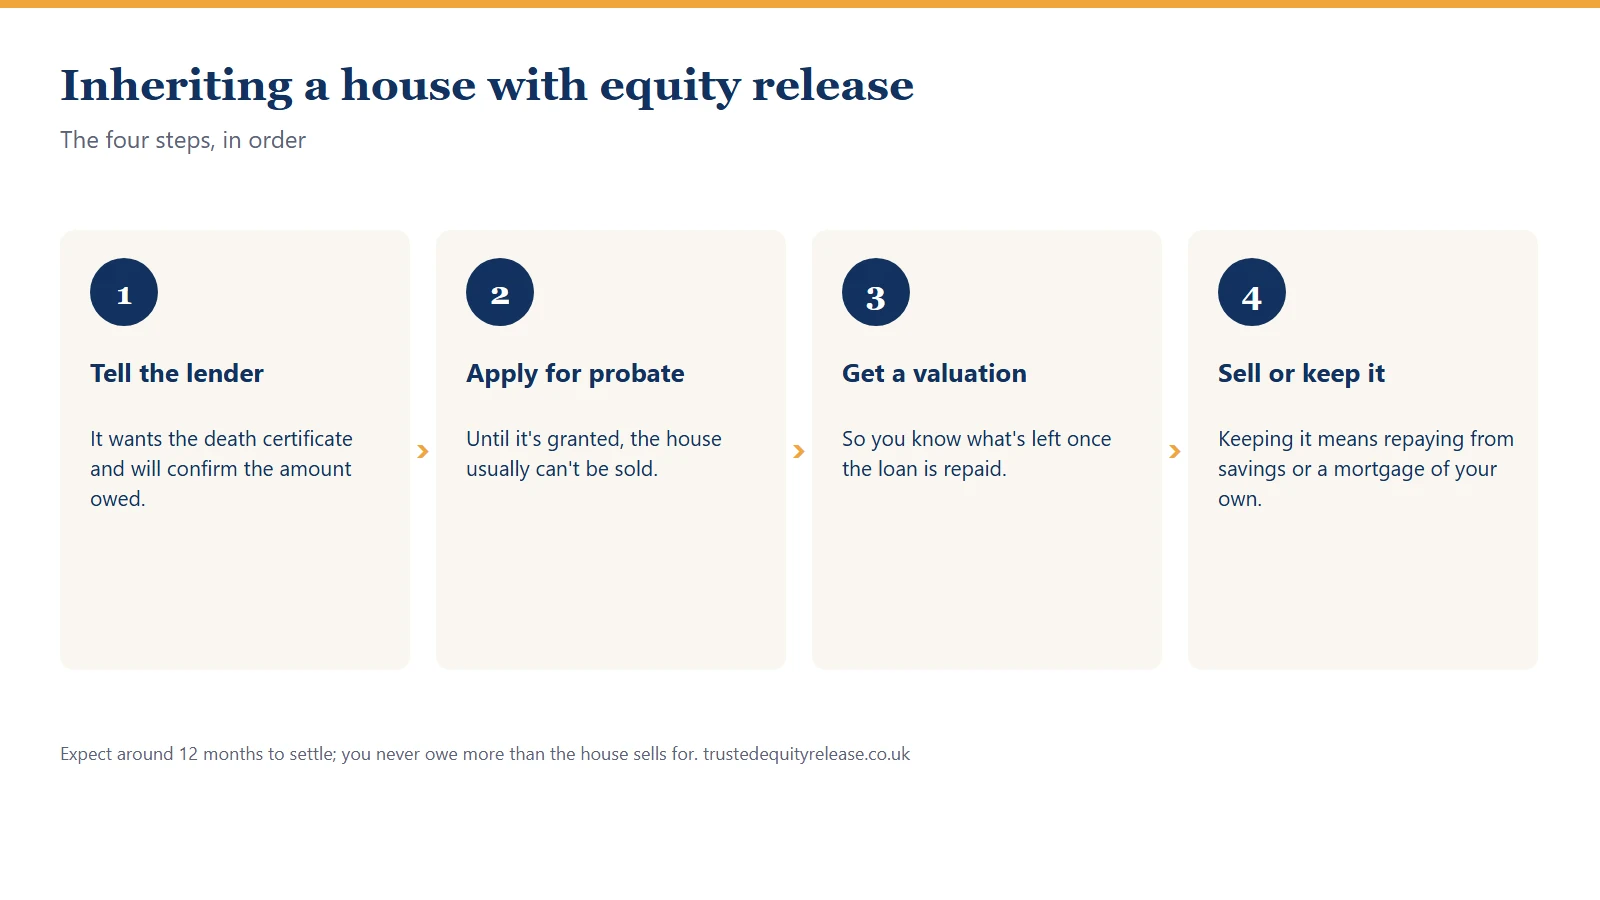
Four steps, in this order:
- Tell the lender. It will want the death certificate, and it will confirm what's owed and ask how the family plans to repay.
- Apply for probate, the legal right to deal with the estate. Until it's granted, the house usually can't be sold.
- Get the house valued, so you know what's left once the loan is repaid.
- Decide whether to sell or keep it, and tell the lender. If a sale is taking time, ask for an extension early: LV=, one of the lenders I compare, says some lenders will extend if they can see the home is being sold.
Can you keep the house?
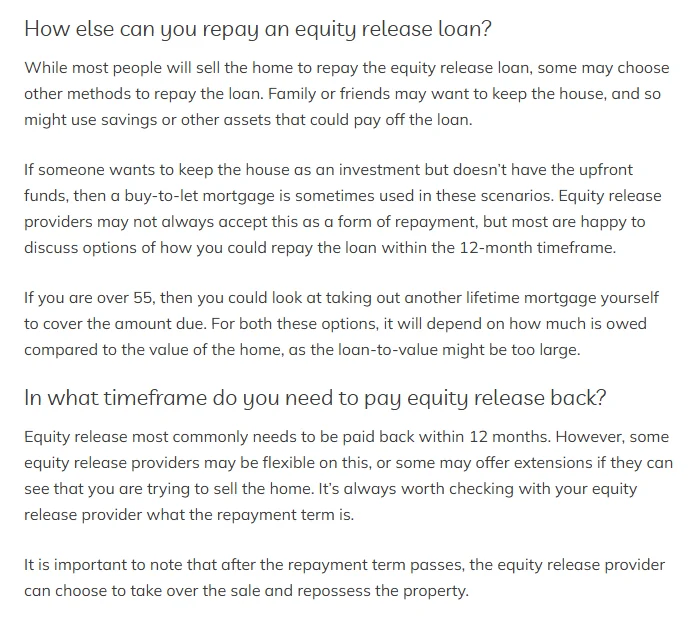
Yes, if the loan is repaid another way. LV= lists the usual routes: savings or other assets, a buy-to-let mortgage if you want to keep the house as an investment, or, if you're over 55, a lifetime mortgage of your own to cover what's owed. Each one depends on how much is owed against what the house is worth.
Will there be anything left to inherit?
In a lot of cases, yes, though less than there would have been. The typical lifetime mortgage starts at around 15% of the home's value, on FCA data from 2022 to 2025, and with nothing paid, compound interest roughly doubles the debt in 11 years at 6.25%. So what's left depends mostly on how long the plan ran and what the house did in the meantime. Some plans also ring-fence a share of the home's value for the family.
Equity release is still small next to what passes down: for every £1 released in 2023-24, £5.80 of homes passed through estates that paid inheritance tax, on the HMRC data in my inheritance and housing wealth statistics. The loan is a debt of the estate, so it reduces the estate's value for inheritance tax, and my page on tax and equity release covers that side.
Why ask me about inheriting a house with equity release?
Because the heirs' side is part of the advice from the start. Before anyone signs, I set out what the family will need to do and how long the lender gives them, and they're welcome in the room. I'm a whole-of-market adviser, I compare the ten lenders I work with, and I'm a member of the Equity Release Council. Trusted Equity Release is a trading name of Pellucid Ltd, authorised and regulated by the Financial Conduct Authority, FRN 981845. Get in touch.
“My grandmother, who had recently lost her husband to cancer, was looking to purchase a new home. Due to delays and reluctant estate executors, probate was proving difficult.”
FAQ
Sources
- LV=: what happens to equity release after death? (12-month repayment, extensions, ways to keep the house; checked 12 Oct 2026; screenshot kept)
- Equity Release Council: product standards (the no negative equity guarantee)
- Trusted Equity Release: equity release statistics (median loan-to-value, FCA)
- Trusted Equity Release: inheritance and housing wealth statistics (£5.80 for every £1, HMRC)
Book your free initial consultation today.
Pick up the phone and speak to Jeremy directly. If equity release is not the right choice, I will say so.
07768 972861 Or try the quick calculator