Home › FAQs › Do you need an adviser?
Do you need an adviser for equity release?
If you're wondering whether you need an adviser for equity release, or whether you could skip the adviser and the fee, you're in the right place, and I'll declare my interest upfront: I am one. The useful news is that the answer does not rest on my opinion. It is written into how this market is regulated, and the fee question has a straighter answer than most firms give.
- Member of the Equity Release Council
- SOLLA Later Life Lending Advice Standard
- Authorised and regulated by the FCA, FRN 981845
Quick answer: can you go straight to a lender?
Not in practice. FCA rules require advice on lifetime mortgages, and most lenders will not deal with the public directly, so an adviser is how a plan actually gets arranged. Every Equity Release Council plan also involves your own solicitor. The real choice is which adviser, not whether.
“If you want someone you can genuinely trust then don't go anywhere else! Jeremy is probably the most honest and genuine advisor that you will come across.”
Why speak to Trusted Equity Release?
Because with me, what you see is who you get. With the big firms you deal with a salesman, it gets passed to an admin, and if there is a problem you are struggling. Here it is me from start to finish: one adviser, face to face, whole of market, and I am not a pushy salesperson. I am an Equity Release Council member, I hold the SOLLA Later Life Lending Advice Standard, and Trusted Equity Release is a trading name of Pellucid Ltd, authorised and regulated by the Financial Conduct Authority, FRN 981845.
The first conversation costs nothing and carries no obligation. Email me, request a printed brochure, or get in touch on the number at the top of this page.
Why is advice compulsory for equity release?
Because a lifetime mortgage is a decision secured on your home, usually made in your seventies, that runs for the rest of your life. The FCA requires advice on these plans so that someone qualified is personally on the hook for the recommendation being suitable, in writing. The market runs that way in practice too: FCA data shows more than 90% of lifetime mortgages are sold through intermediaries, and the picture is on my equity release statistics page. This is not a product with a checkout button, and the day it becomes one is the day to worry.
The two advisers you will actually use
People searching this question often mean two different professionals, and you will use both.
- A financial adviser finds and recommends the plan. I compare every lender's terms on your case, put the recommendation in writing, and answer for its suitability.
- Your own solicitor gives you independent legal advice before you sign. That is an Equity Release Council requirement, and the Council's own guidance is blunt that the solicitor cannot tell you whether the plan is suitable. Different job.
One practical note from my cases: use a solicitor who handles equity release regularly. I can recommend one who does it day in, day out. Clients who insist on a general high street firm usually come to regret it, because an unfamiliar solicitor is the commonest cause of delay I see.
How much does equity release advice cost?
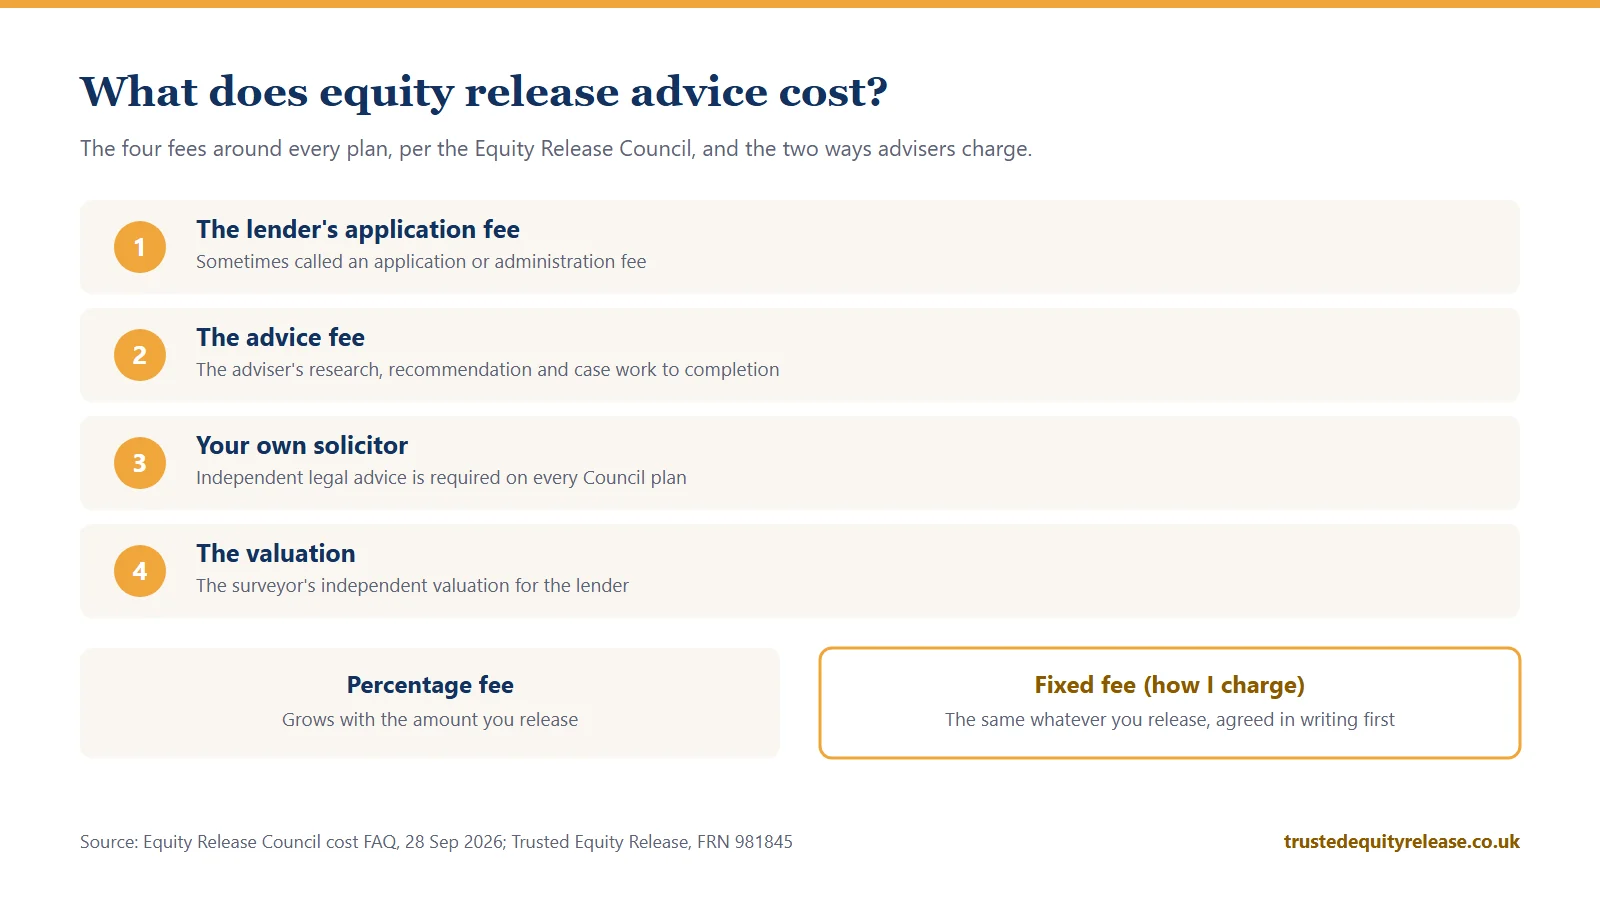
Advisers charge one of two ways: a percentage of the amount you release, or a fixed fee. A percentage grows with the release; on larger cases the difference runs to thousands, so it is the first thing to ask. The Equity Release Council lists the full cost of setting up a plan as four fees: the lender's application fee, the advice fee, your solicitor, and the valuation. Levels vary between firms, and in the Council's own words some adviser firms do not charge any advice fee at all, so ask what you are getting for what you are paying.
Mine is a fixed fee, the same whatever you release, agreed in writing before any work starts, and I will tell you the number in the first phone call. There is nothing to pay unless your case completes.
What does the advice fee actually pay for?
The work between "I'm curious" and money in your bank. A proper fact find, including the health questions that can improve an equity release lender's terms. A whole-market comparison on your actual case. A written recommendation and personalised illustration you can put in front of your family. Then the unglamorous part: chasing the application process, the valuation and the legal work through to completion, one person answerable for the lot. And it is a lifetime fee: once your plan is set up, my help afterwards costs you nothing.
If the honest answer is that equity release is not right for you, the recommendation says so, and one of my Google reviews describes exactly that: an application cancelled at no charge when the client no longer needed it, with, in the reviewer's words, no cancellation fees, no resentment, and no animosity.
What are equity release interest rates at the moment?
Advertised lifetime mortgage rates start from about 6.25% MER in September 2026, and the rate on your own illustration depends on age, property and loan size. I track the market monthly on my equity release interest rates page, and picking the right lender for your case is most of what the comparison is for.
FAQ
Is the first conversation with an equity release adviser free?
Can the advice fee be paid from the money you release?
Does a bigger release mean a bigger advice fee?
What is SOLLA, and why does it matter for later-life advice?
Do you need a solicitor as well as an adviser?
What happens if the adviser says equity release is not right for you?
Book your free initial consultation today.
Pick up the phone and speak to Jeremy directly. If equity release is not the right choice, I will say so.
07768 972861 Or try the quick calculator