Home › Mortgages for over 50s
Mortgages for over 50s
If you're looking for a mortgage in your 50s, you're in the right place. I arrange the later-life options myself, and my colleagues at Pellucid, the same firm, arrange ordinary mortgages, so one firm can compare every route open to you.
- On the FCA register, reference JLF01060 check the register
- Pellucid Ltd, FCA number 981845 check
- Equity Release Council member my profile
- SOLLA Later Life Lending Advice Standard
Quick answer: how long can a mortgage run if you're over 50?
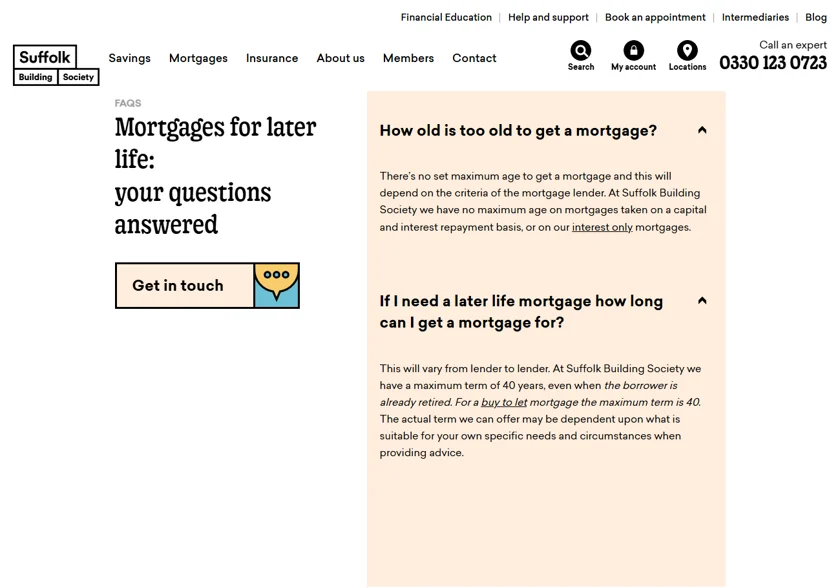
Up to the lender's age limit for the end of the term: 75 at Nationwide, 80 at Halifax and HSBC, 95 at Family Building Society, and none at Suffolk Building Society. Santander and NatWest also end the term at your planned retirement age if you're still working.
Why ask me about a mortgage in your 50s?
Because I arrange the later-life routes myself: retirement interest-only and term interest-only mortgages from 50, payment term lifetime mortgages from 50 and lifetime mortgages from 55, across the whole market. For an ordinary mortgage, my colleagues at Pellucid, the same firm, do the arranging, so whichever route fits, it starts with one conversation. I've specialised in later-life lending since 2009 and I'm a member of the Equity Release Council. Trusted Equity Release is a trading name of Pellucid Ltd, authorised and regulated by the Financial Conduct Authority, FRN 981845. Email me, request a printed brochure, or get in touch.
“Excellent, professional and friendly service, we highly recommend Jeremy. He was very quick to reply to our enquiry and kept us posted at all times during the process. Thanks so much for all your help.”
Can you get a mortgage in your 50s?
Yes, and getting a mortgage that runs into retirement is normal now. In 2024 Q1, 42% of new UK mortgage lending ran beyond the borrower's 67th birthday, up from 27% in 2019 Q1, according to Bank of England staff analysis of FCA data. Around 6% of standard mortgage sales each year go to borrowers aged 55 or over who will be 68 or over when the term ends, about 350,000 sales since 2021 (FCA). Both figures are on my page of statistics on lending into retirement.
Long terms are normal at every age. 62% of first-time buyers in England with a mortgage took a term of 30 years or more in 2024-25, up from 47% five years earlier, according to A Little Mortgage Advice's first-time buyer statistics. In your 50s, what limits the term is the lender's maximum age at the end of it.
What is the maximum age for a mortgage?
Each lender sets its own, and the age when the term ends matters more than your age when you apply. These are the limits on each lender's own site, checked on 7 October 2026:
| Lender | Mortgage must end by | Interest-only must end by | If you're still working |
|---|---|---|---|
| Nationwide | before the oldest borrower's 75th birthday | retirement, or 70 at the latest | maximum retirement age 70 |
| Santander | 75th birthday | 70th birthday | the term can't run past your intended retirement age |
| NatWest | 75 | 70 | no lending into retirement: the term stops at your intended retirement age |
| Halifax | 80 | 70 | retirement income verified past your retirement or working age (normally 75) |
| Barclays | the oldest borrower's 80th birthday | 75 (70 above half the home's value) | maximum retirement age 75 |
| HSBC | the day before your 80th birthday | the day before your 70th | no new lending once any borrower is 70; pension projections within 10 years of 70 |
| Nottingham Building Society | 75 (85 on its Make it Possible range) | not stated separately | assumes you retire at 68 |
| Leeds Building Society | 85 | retirement, or 70 at the latest | maximum retirement age 70 |
| Family Building Society | 95 | 94 | earned income usually counted to 70 (75 for professionals) |
| Suffolk Building Society | no maximum | no maximum | pension income assessed past retirement; over-75s need independent legal advice |
For older borrowers, the big banks cluster at 75 to 80 and watch your retirement date, while the building societies range from 75 at Nottingham to no limit at all at Suffolk. If you're still working, the retirement rule can bite before the age limit does. If you've already retired, it falls away: NatWest and Santander both consider retired applicants within their age limits. Lenders change these limits, so they're checked again before any recommendation.
What do lenders check about your income in retirement?
Affordability: whether your income covers the payments for the whole term, including the years after you stop work. If the term runs past your planned retirement, the lender wants evidence of your pension income, and some test it years ahead: HSBC asks for pension projections once you're within 10 years of 70, Leeds and Nationwide use the lower of your current and expected pension income as retirement nears, and Nottingham Building Society assumes you'll retire at 68.
If the numbers don't stretch, the usual answers are a shorter term with bigger payments, a retirement interest-only mortgage, or, from 55, a lifetime mortgage, which needs no income test on a roll-up plan.
What are your options over 50?
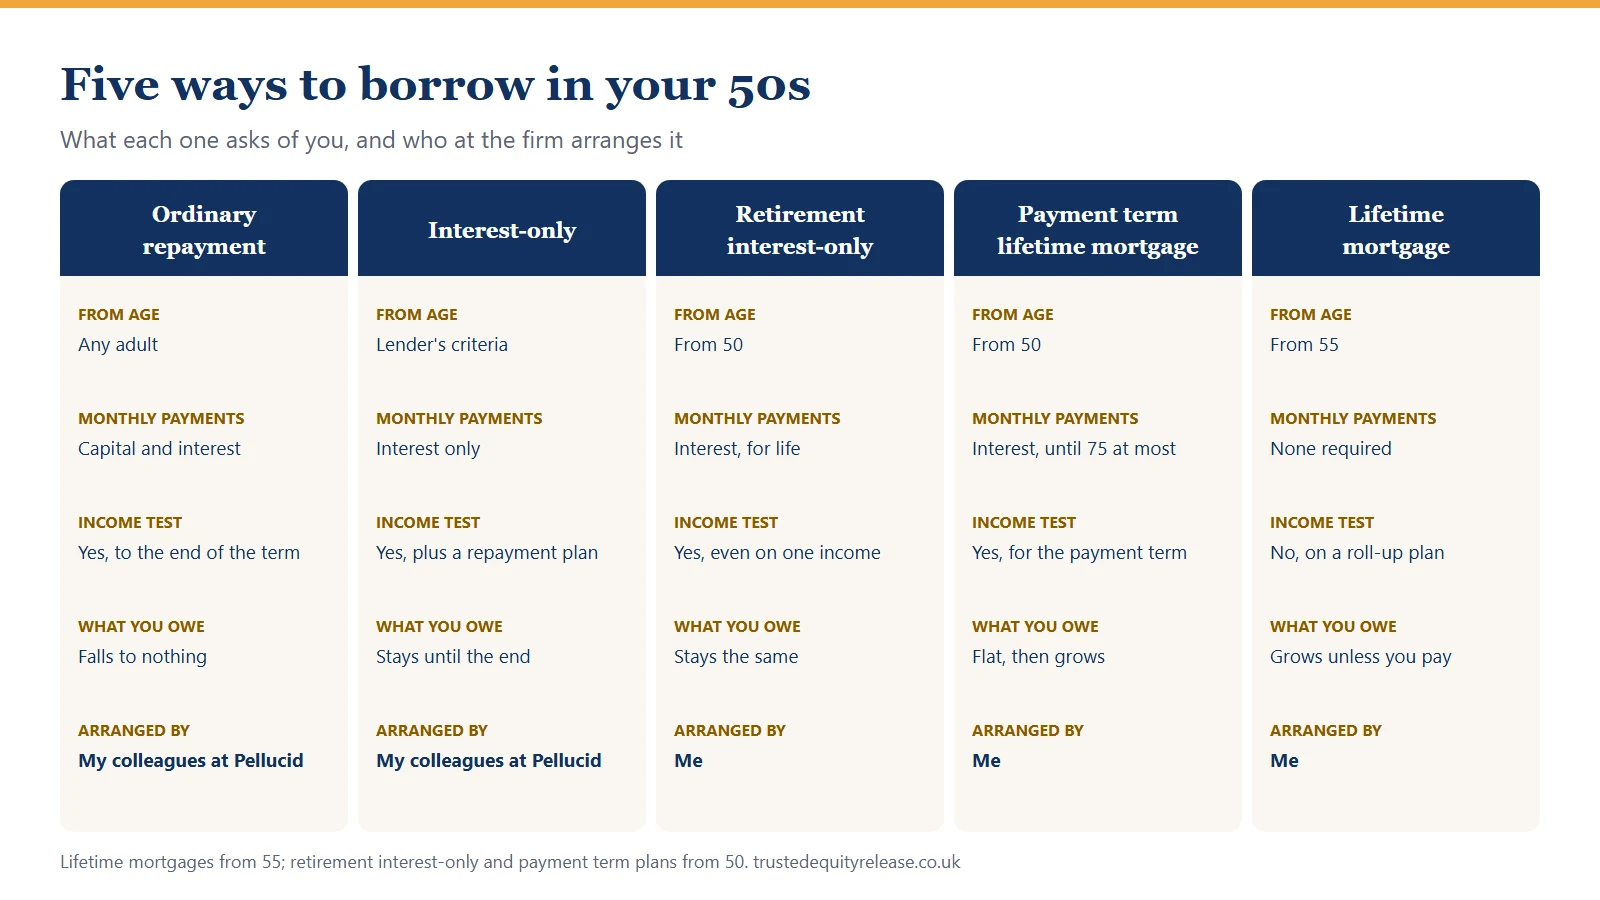
Five routes, and the right one depends on your income now and in retirement:
| Ordinary repayment | Interest-only | Retirement interest-only | Payment term lifetime mortgage | Lifetime mortgage | |
|---|---|---|---|---|---|
| From what age | Any adult | Lender's criteria | From 50 | From 50 | From 55 |
| Monthly payments | Capital and interest | Interest, plus a plan to repay | Interest, for life | Interest, up to age 75 at most | None required |
| Income test | Yes, to the end of the term | Yes, and the repayment plan | Yes, including on one income | Yes, for the payment term | No, on a roll-up plan |
| What you owe | Falls to nothing | Stays until the end | Stays the same | Flat, then grows | Grows unless you pay |
| Arranged by | My colleagues at Pellucid | My colleagues at Pellucid | Me | Me | Me |
The three later life mortgages each have their own page: how a retirement interest-only mortgage works, the payment term plan under borrowing before 55, and how a lifetime mortgage works.
Is it a good idea to take a mortgage in your 50s?
It can be, if the payments suit your income now and your pension later. A longer term lowers the monthly payment but adds interest overall, so the shortest term you can comfortably afford costs least. The risk is reaching retirement with a payment you can't meet: in 2024, 9% of UK residential mortgage holders aged 55+ said they did not think they could afford their mortgage payments in retirement and did not know what they would do (FCA Financial Lives).
Sometimes the better answer is a shorter term, or downsizing to a smaller property, and I'll tell you if I think so.
FAQ
Can a 54-year-old get a 25-year mortgage?
Can someone in their 50s get a 30-year mortgage?
Does Nationwide still offer mortgages for over 50s?
Can you still get a mortgage at 60?
Can you remortgage in your 50s?
Can you get equity release at 50?
What if your interest-only mortgage is ending?
Sources
- MoneyHelper: what happens to your mortgage when you retire? (updated 6 Oct 2026)
- Lender criteria, each read on the lender's own site on 7 Oct 2026, screenshots kept: Nationwide, Nationwide retirement mortgages, Halifax, Barclays, Santander, NatWest, HSBC, Nottingham Building Society, Leeds Building Society, Family Building Society, Suffolk Building Society
- Bank Underground (Bank of England staff blog), 17 Oct 2024: 30+ year mortgages (the 42% figure; staff analysis of FCA data, not an official Bank statistic)
- Trusted Equity Release: retirement mortgage debt statistics (FCA sales data, FCA Financial Lives, UK Finance)
- A Little Mortgage Advice: UK first-time buyer statistics (English Housing Survey 2024-25)
Book your free initial consultation today.
Pick up the phone and speak to Jeremy directly. If equity release is not the right choice, I will say so.
07768 972861 Or try the quick calculator