Home › Where I work › Harrogate
Lifetime mortgage adviser for Harrogate: can you get proper advice by phone or video?
If you're looking for a lifetime mortgage adviser for Harrogate, you're in the right place. I'm Jeremy Furnell, a whole-of-market later-life adviser, and I'll be straight with you from the first line: I'm based just outside March in Cambridgeshire, 120 miles from Harrogate as the crow flies, so I won't be coming to your house. I advise Harrogate homeowners by phone, or by video if you'd prefer it.
- On the FCA register, reference JLF01060 check the register
- Pellucid Ltd, FCA number 981845 check
- Equity Release Council member my profile
- SOLLA Later Life Lending Advice Standard
Quick answer: can I get lifetime mortgage advice in Harrogate without a home visit?
Yes. I'm a whole-of-market adviser based near March, 120 miles away, so I advise by phone, or video if you prefer, and post you the paperwork. The lender's valuer still visits your home, and the legal stage is done by a solicitor you choose, which can be a Harrogate firm.
Why speak to Jeremy about a lifetime mortgage in Harrogate?
Because the person who answers the phone is the person who does the fact-find, writes the recommendation, fills in the application with you and is still there on completion day. With the bigger firms you often talk to one person and are then passed to an administrator. With me there's nobody to pass you to, and that matters more, not less, when we're talking on the phone rather than across a table.
I've worked in financial services since 1996 and in later-life lending since 2009. I hold CeMAP and CERT CII (ER), I hold the SOLLA Later Life Lending Advice Standard, and I belong to the Equity Release Council, which since April 2026 has asked its advisers to pass an exam every year to stay in. I compare plans from the lenders I work with across the whole market, and those lenders lend across England, Harrogate included.
The review below was written by a grandson who joined his gran's first meeting by phone from another county, which is roughly how a Harrogate family would join in. Trusted Equity Release is a trading name of Pellucid Ltd, authorised and regulated by the Financial Conduct Authority, FRN 981845.
“He swiftly arranged an initial meeting with my gran and mother, while also including me via phone, as I was in another county. This demonstrated complete transparency and secured my trust in him.”
Why would anyone in Harrogate use an adviser 120 miles away?
Because a lifetime mortgage is a national product, and the advice is the part that matters. The lenders, the products and the rules are the same in HG1 as they are in the Fens. What changes with distance is the meeting, not the plan.
That said, I'm not going to pretend distance costs you nothing. Here is the honest comparison:
| Me, by phone or video | A Yorkshire adviser who visits | |
|---|---|---|
| Who you deal with | Me, from first call to completion | Depends on the firm; ask |
| Which lenders | Whole of market | Ask whether it's whole of market or a panel |
| First meeting | Phone, or video if you'd prefer | At your kitchen table |
| Paperwork | Posted to you, and we go through it on the phone | Handed to you in person |
| Family | On the call, from wherever they live | In the room, or on the phone |
| The valuation | The lender's valuer visits your home | The same |
| The legal stage | A solicitor you choose, local or specialist | The same |
| If something goes wrong later | You ring the same number | You ring the firm |
There are equity release advisers based in Harrogate and Leeds who make home visits, and if sitting face to face matters to you, one of them will serve you better than I can on that point. I'd rather you knew that now than found it out halfway through.
How does lifetime mortgage advice by phone work, step by step?
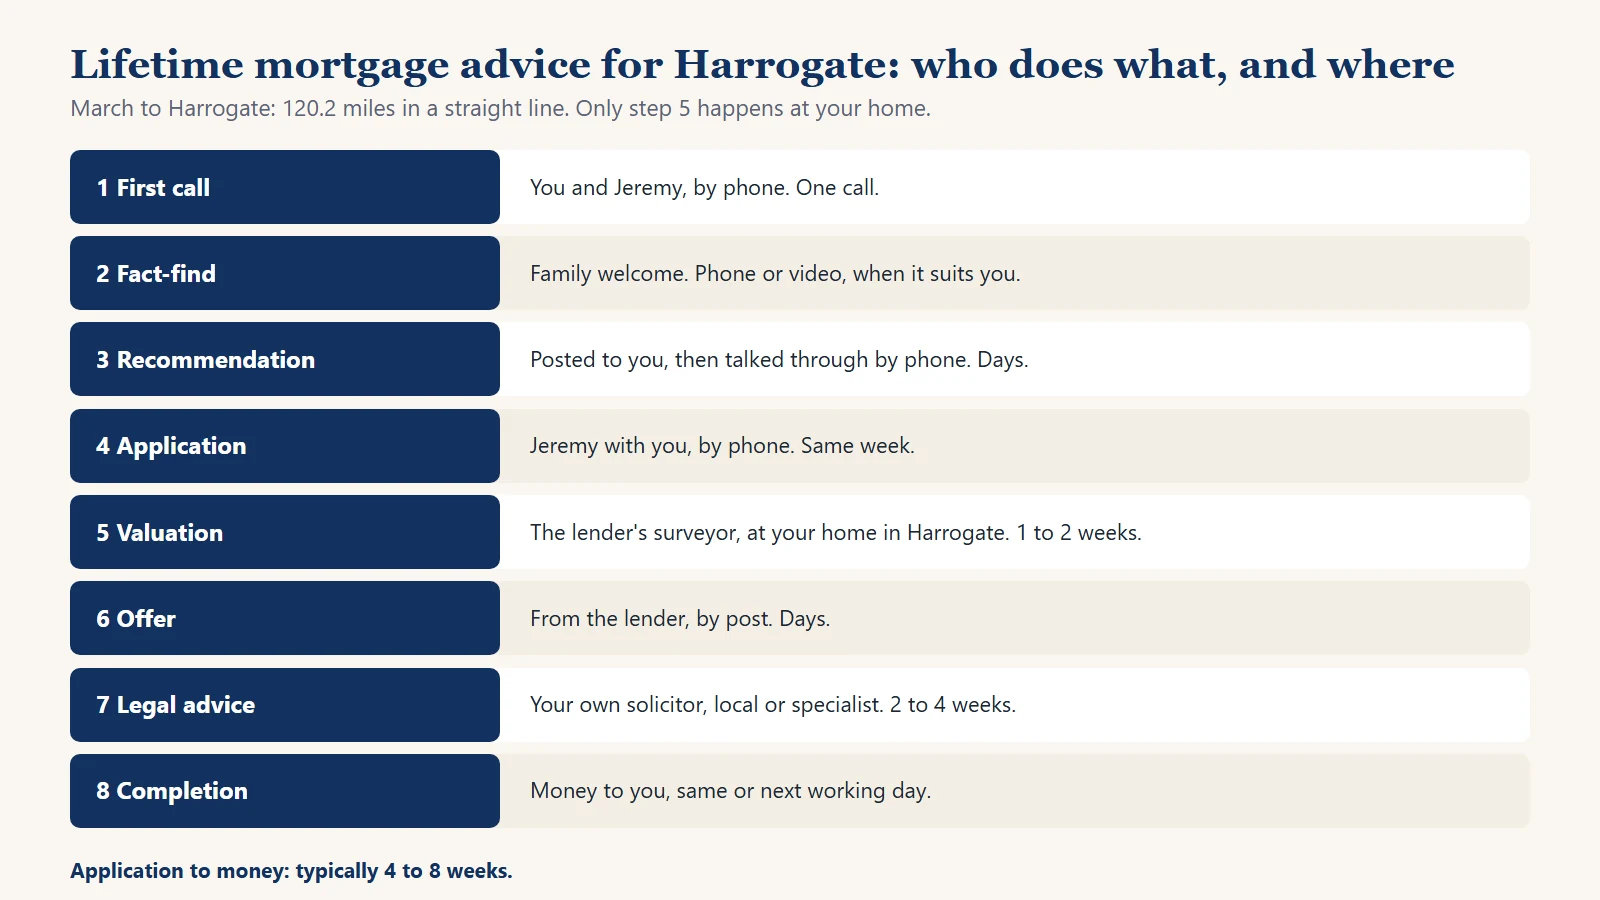
It follows the same eight steps as a home-visit case. The only differences are how we talk and how the paper reaches you. The advice stage runs at your pace; from the application going in to the money landing, four to eight weeks is normal for a lifetime mortgage, and the legal stage usually sets the pace.
| Step | Who does the work | Where it happens | Typical time |
|---|---|---|---|
| 1. First phone call | You and me | Phone | One call |
| 2. Full fact-find | You and me, family welcome | Phone, or video if you'd prefer | Arranged when it suits you |
| 3. Recommendation and illustration | Me | Posted to you, then talked through by phone | Days, at your pace |
| 4. Application | Me, with you | Phone, with the forms in front of us both | The same week you decide |
| 5. Valuation | The lender's surveyor | Your home in Harrogate | 1 to 2 weeks to happen |
| 6. Offer | The lender | Post | Days after the valuation |
| 7. Independent legal advice | Your solicitor | Your solicitor's office, or remotely if they offer it | 2 to 4 weeks |
| 8. Completion | Lender and solicitor | Money paid to your solicitor, then to you | Same or next working day |
Step 1: a free phone call to see if I can help
You ring me, or fill in the contact form and I ring you back. On that first call I'm only finding out whether I can help: how old you both are, roughly what the house is worth, what's left on any mortgage and what the money is for. If a lifetime mortgage clearly isn't the answer, I'll tell you on that call, and it has cost you nothing.
Step 2: the full fact-find, with your family on the line
This is the long conversation, usually an hour or more, and it's the one I'd normally have at a kitchen table. We go through your income, benefits, health, debts, your plans for the house and what you want to leave your family. Your son or daughter can join from wherever they live, on the phone or on video. It helps to have your ID, a recent council tax bill and the details of any mortgage or secured loan beside you, because missing paperwork is a common cause of delay later.
Step 3: my recommendation, on paper, through your letterbox
I search the whole market, then send you a written recommendation and the lender's Key Facts Illustration, which shows the rate, the fees and how the debt grows year by year. I post it, because I'd rather you had paper to read and write on than a PDF on a phone screen, and then we go through it line by line on the phone. If the right answer is a cheaper alternative, or "not yet", that's what the recommendation says.
Step 4: the application, which we fill in together
Once you've decided, I send the application to the lender, usually the same week. The forms are long. We complete them together over the phone, each with a copy in front of us; one of my reviews describes me helping a grandmother through exactly that, although that one was in person. Tell me about any health conditions at this stage, because some lenders improve their terms for them, and disclosing late can mean starting again.
Step 5: the lender's valuation, at your home
This is the one step that always happens at your house. The lender sends its own surveyor to value it, and that normally happens within one to two weeks. If the figure comes in lower than expected, the offer is reworked on the lower figure, and I'll ring you to go through what that means before anything else happens.
Step 6: the formal offer
The lender's offer usually follows the valuation within days and arrives by post. Offers have a validity period, so this is where I start chasing everyone to keep the case moving.
Step 7: independent legal advice, from a solicitor you choose
You must have your own solicitor, who explains the plan and what it means for your estate before you sign. It can be a Harrogate firm you already know, or I can recommend the specialist firm I use, which does equity release day in, day out. The choice is yours. In my experience a general high street firm that rarely handles equity release is the commonest reason a case slows down, so if you go local, ask them how many of these they do. Expect two to four weeks here.
Step 8: completion, and the money reaching you
On completion day the lender sends the money to your solicitor, who pays off any existing mortgage first and transfers the rest to you, normally the same day or the next working day. After that I'm still your adviser for the life of the plan, on the same phone number.
Will you ever come to Harrogate in person?
Not as a matter of course. I make home visits within 70 to 80 miles of March, across Cambridgeshire, Norfolk, Suffolk, south Lincolnshire and Northamptonshire, and Harrogate is well outside that. I'll be honest about why I mention it at all: I prefer the kitchen table. I like to hand people paper and go through it face to face, and I'm not a natural on camera. A lot of my clients, wherever they live, are happiest with a phone call anyway.
So on this page you're getting the phone version of me, done properly: the same fact-find, the same recommendation and the same paperwork, with more of it coming by post.
Can my family join the call from wherever they live?
Yes, and I'd like them to. A lot of the people I help have a son or daughter involved, and in Harrogate that relative may well live further away than I do. They can join the phone call, or the video call if you'd prefer one, and I'm happy to copy them into my letters and emails with your permission. Hearing the plan first-hand saves a lot of second-hand worry later.
How can I check that a phone-based adviser is genuine?
Check the register before you tell anyone anything about your finances. Equity release can only be arranged with advice, and the adviser's firm has to be on the Financial Conduct Authority's register. Look up Pellucid Ltd, FRN 981845, and check that the name, number and contact details match the ones you're using to reach me.
| Check | Where | What you should see for me |
|---|---|---|
| FCA authorisation | The FCA register | Pellucid Ltd, FRN 981845, trading as Trusted Equity Release |
| Equity Release Council membership | The Council's adviser search | Jeremy Furnell |
| Who you'll deal with | Ask on the first call | The same person throughout |
| How the adviser is paid | Ask on the first call, and get it in writing | A fixed fee on completion, not a percentage |
There's more on why you need an adviser for equity release, and on how to find a trustworthy equity release adviser, whoever you end up using.
How does a lifetime mortgage work?
A lifetime mortgage lets you take tax-free money from your home without moving out. It's a loan secured on your home, available from age 55, where you keep owning the house, nothing has to be paid each month, and the loan plus interest is repaid from the sale when the last of you dies or moves into long-term care.
You can take the money in one go, or take a smaller first sum with a reserve to draw on later and pay interest only on what you've drawn. A lot of plans also let you pay some or all of the interest each month if you'd like to keep the debt from growing. Any mortgage you still have is paid off first, out of the release.
There are two types of equity release: lifetime mortgages and home reversion, where you sell part or all of the house to a provider. I advise only on lifetime mortgages, and I'm happy to explain the difference. How lifetime mortgages work, and what I check before recommending one, has a page of its own.
Is equity release safe?
Yes, in the ways that protect your home, and it's more tightly controlled than a lot of people expect. The FCA's rules list what an adviser must weigh before recommending it, including your benefits, your tax, your health, cheaper alternatives and what you want to leave your family. Every lifetime mortgage from an Equity Release Council member also has to meet the Council's product standards:
| Protection | What it means for you |
|---|---|
| Fixed or capped interest rate | The rate is fixed, or capped, for the life of the loan |
| Home for life | You can live there for the rest of your life, or until you move into long-term care |
| Right to move | You can move house and take the plan with you, if the new home meets the lender's criteria |
| No negative equity guarantee | Your estate never owes more than the home sells for |
| Penalty-free partial repayments | You can pay some back without a charge, within the lender's limits |
| Independent legal advice | A solicitor explains the plan to you before anything completes |
The real risk isn't losing your home. It's the debt growing faster than people expect, which I show in figures below. More on how safe lifetime mortgages are.
What are homes in Harrogate worth?
The Land Registry's index doesn't publish a separate figure for Harrogate any more. Since April 2023 the town has been part of North Yorkshire Council, and the index reports that whole council area as one. Its latest month, August 2026, looks like this:
| North Yorkshire Council area, August 2026 | Average price |
|---|---|
| All homes | £270,080 |
| Detached | £431,122 |
| Semi-detached | £269,527 |
| Terraced | £219,836 |
| Flats and maisonettes | £142,783 |
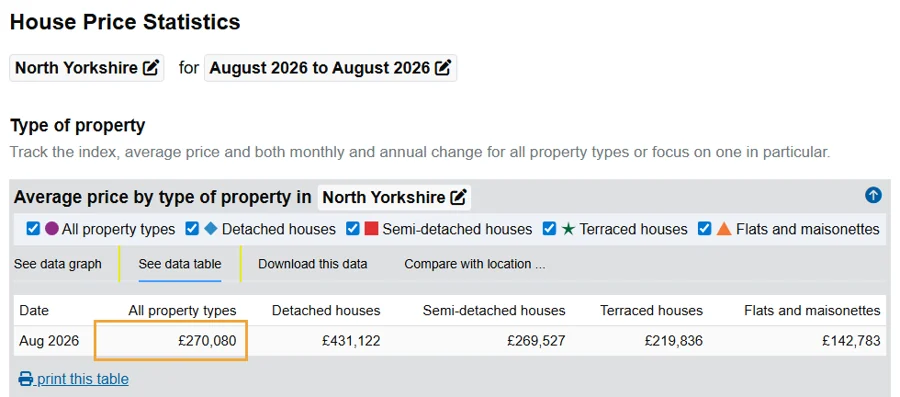
Prices were 1.7% higher than a year earlier. A county average covers a Dales cottage and a Harrogate villa alike, so treat it as a starting point; the figure that counts is the one the lender's valuer puts on your own home.
The 2021 Census was taken before the merger, so it still shows the old Harrogate district on its own. Of its 24,214 households headed by someone aged 65 or over, 18,458 owned their home outright: 76.2%, against 71.0% across England. Another 1,635, or 6.8%, still had a mortgage or loan on it. I've written up the national picture in my page about older homeowners' housing wealth.
How much could I release from a Harrogate home at my age?
It depends on the age of the youngest owner and on your home. To show what the typical lender maximums mean in pounds, here they are applied to the August 2026 North Yorkshire averages. This is an illustration only, not an offer and not a figure for your home:
| Youngest owner's age | Typical maximum | On £270,080 (all homes) | On £431,122 (detached) |
|---|---|---|---|
| 55 | 25% to 28% | about £68,000 to £76,000 | about £108,000 to £121,000 |
| 70 | 40% to 43% | about £108,000 to £116,000 | about £172,000 to £185,000 |
| 80 and over | 50% to 57% | about £135,000 to £154,000 | about £216,000 to £246,000 |
Those are ceilings, and people usually take far less: FCA data for 2022 to 2025 puts the median lifetime mortgage at around 15% of the home's value. Any mortgage still on the house comes off the top. My calculator gives an indicative figure in three questions, with no name or phone number needed.
How fast does a lifetime mortgage debt grow?
Quicker than it feels at the start, which is why I put these numbers in front of every family. This is my calculator's example, with nothing paid back:
| £60,000 borrowed at 6.25% a year, compounded monthly (illustration) | Owed |
|---|---|
| At the start | £60,000 |
| After 10 years | about £111,900 |
| After 15 years | about £152,800 |
| After 20 years | about £208,700 |
That compounding is what shrinks the inheritance. You can slow it by paying some of the interest each month, making penalty-free partial repayments, or taking a smaller first sum with a drawdown reserve. You can see what lenders are charging this month before we talk.
What does it cost, and how am I paid?
The interest is by far the biggest cost. The rest comes from several places:
| Cost | Paid to | When | Worth knowing |
|---|---|---|---|
| Advice | The adviser, as a fee, or by the lender as commission | On completion | Ask which, in writing, before you go ahead |
| Legal fee | Your solicitor | On completion | Compulsory, whichever firm you use |
| Valuation | The lender's surveyor | Before the offer | Some lenders charge it, some don't |
| Arrangement or completion fee | The lender | On completion | Charged by some lenders, not all |
| Interest | The lender | Added to the loan each month | The largest cost over time, unless you pay it as you go |
| Early repayment charge | The lender | Only if you repay early | Check how long it lasts and when it doesn't apply |
Here is how I'm paid, and it's the same in Harrogate as in March. The first conversation is free, and you pay me nothing unless your plan completes. My fee is fixed, not a percentage of what you borrow, it can be taken from the money released, and it covers you for the life of the plan. I'll tell you the figure on the phone, and I'll give you the full cost, solicitor included, before you commit. Living further away doesn't add anything to it.
Who can get a lifetime mortgage in Harrogate?
If you're 55 or over and own your home, you usually can, but the lender looks at the person and the property:
| Rule | What lenders look for |
|---|---|
| Age | The youngest owner is 55 or over |
| Your home | It's your main residence and you own it |
| Value | Usually worth at least £70,000 |
| Construction | Standard construction gets the full figures; non-standard builds, flats above shops and ex-local-authority blocks may get less or be declined |
| Leasehold flats | Lenders want enough years left on the lease |
| Existing mortgage | It must be paid off from the release |
| Health | Not a barrier, and it can improve the terms with some lenders |
The full checklist is on am I eligible for equity release. If your home has a lot of land, an annexe or anything unusual about it, mention it on the first call, because it narrows the list of lenders and I'd rather know before the valuer does.
How will it affect my family's inheritance and my benefits?
It reduces what you leave, and it can affect means-tested benefits such as Pension Credit if you take a large lump sum and hold it as savings. Both are reasons I look at drawdown, and both are reasons I want your family involved.
The people who complain about equity release are rarely the people who took it out. It's the children, years later, when the inheritance is smaller than they'd hoped. With a client 120 miles away that's even more reason to get them on the call early. Some plans also let you protect part of the home's value as a guaranteed inheritance, though that lowers what you can borrow. More on whether your family ends up in debt, and on whether you pay tax on equity release before you gift any of it.
Is there a better option than equity release?
Sometimes, and I'll tell you if there is. The first thing I tell people is that equity release is Marmite: you'll either love it or hate it.
| Option | When it can beat equity release |
|---|---|
| Downsizing | You'd be happy to move, and a smaller home frees enough cash |
| Retirement interest-only mortgage | Your income comfortably covers the monthly interest; available from 50, though they're hard to get |
| Help from family | Someone can lend or gift what you need |
| Benefits you aren't claiming | A benefits check finds income you're missing |
| Using savings first | The sum is small and savings cover it |
I've set out the alternatives I weigh first, and when each one wins. A retirement interest-only mortgage has its own page.
FAQ
Is advice by phone as thorough as a home visit?
Do I have to use a solicitor near you in Cambridgeshire?
Can I get a lifetime mortgage if I still have a mortgage?
How long does it take when the advice is by phone?
Do you advise elsewhere in Yorkshire, such as Knaresborough, Ripon, York or Leeds?
How far is Harrogate from March, and why does it matter?
Harrogate is 120.2 miles from March in a straight line, and further by road. That's why this page offers phone and video advice rather than the home visits I make closer to home, where my home-visit area reaches as far as Brackley in Northamptonshire, about 64 miles away.
| From March to | As the crow flies | How I advise |
|---|---|---|
| York | 108.9 miles | Phone, or video if you'd prefer |
| Leeds | 109.5 miles | Phone, or video if you'd prefer |
| Knaresborough | 119.4 miles | Phone, or video if you'd prefer |
| Harrogate | 120.2 miles | Phone, or video if you'd prefer |
| Ripon | 128.1 miles | Phone, or video if you'd prefer |
If you live closer to Cambridgeshire, or you have family there who'd like to sit in on a meeting, the places I visit at home are listed on my coverage page. And whenever you're ready, get in touch for the free first call.
Final thoughts from me
If you're in Harrogate and weighing up a lifetime mortgage, these are the points I'd want you to take away:
- I advise Harrogate homeowners by phone, or video if you'd prefer, because March is 120 miles away and I don't make home visits there.
- The advice, the lenders and the fee are the same as for a client on my doorstep, and the first conversation is free.
- The lender's valuer visits your home, and the legal stage is done by a solicitor you choose, which can be a Harrogate firm.
- What you can release depends on the youngest owner's age and your own home, and people usually take far less than the maximum.
- Unpaid interest compounds, so the debt grows and leaves less for your family.
- If a face-to-face meeting matters most to you, a Yorkshire adviser who visits at home will suit you better, and that's fine.
How much could you release from your home?
Three quick questions and an indicative figure straight away. No name, phone number or email needed to see it.
What clients and their families say
"Many companies take advantage of the elderly, but this was clearly not the case with Jeremy. He thoroughly explained all options and even assisted my gran with completing complex application forms. Within a week of the initial visit, my gran secured funding from a reputable lender."
"Had the pleasure of dealing with Jeremy on behalf of my mum for equity release on her home. If you want someone you can genuinely trust then don't go anywhere else! Jeremy is probably the most honest and genuine advisor that you will come across."
"Jeremy was very professional throughout the process, kept us uptaded at all times, nothing was too much trouble."
Book your free initial consultation today.
Pick up the phone and speak to Jeremy directly. If equity release is not the right choice, I will say so.
07768 972861 Or try the quick calculator