Home › About Jeremy
Meet your adviserAbout Jeremy Furnell, later life lending specialist
If you're looking to find out who you'd be dealing with before you pick up the phone, you're in the right place. I'm the only adviser at Trusted Equity Release, so the person on this page is the person who answers your call and sits at your kitchen table. Everything I claim below links to the register that proves it.
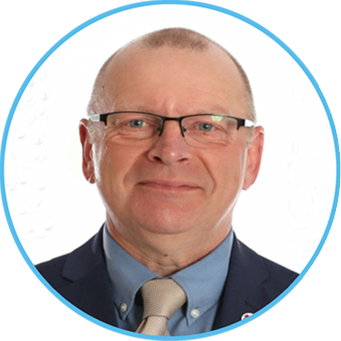
Quick answer: who is Jeremy Furnell?
I'm an equity release adviser based near March, Cambridgeshire. I've worked in financial services since 1996, qualified in equity release with the Chartered Insurance Institute in 2009, and have run my own firm, Pellucid Ltd, since 2010. You'll find me on the FCA register under reference JLF01060.
How can you check me?
Every claim on this page can be checked in a minute or two, on the registers that matter:
| What | Check it here | What it shows |
|---|---|---|
| Me, on the FCA register | FCA register: Jeremy Leonard Furnell, JLF01060 | My roles at Pellucid Ltd since 16 January 2023, and in the regulator's words: "No FCA or PRA disciplinary or regulatory action" (checked 30 September 2026) |
| My firm | FCA register: Pellucid Ltd, FRN 981845 | Pellucid Ltd is authorised and regulated by the Financial Conduct Authority. Trusted Equity Release is one of its trading names |
| My company | Companies House: Pellucid Ltd, 07174383 | I've been its director since the day it was formed, 2 March 2010 |
| The Equity Release Council | My member profile | Membership, which commits me to the Council's standards, including the no negative equity guarantee |
| SOLLA | SOLLA's find-an-adviser directory | The Later Life Lending Advice Standard |
| My clients | My Google reviews | All six reviews, every one five stars, with my replies |
What am I qualified in?
Equity release needs a qualification of its own, on top of a mortgage one. As I put it, "you have to be qualified to do equity release, more so than a normal mortgage adviser." Mine:
| Qualification or standard | When |
|---|---|
| Certificate in Equity Release (CERT CII (ER)), the Chartered Insurance Institute | 2009 |
| Certificate in Mortgage Advice and Practice (CeMAP), The London Institute of Banking & Finance | 1999 |
| Financial Planning Certificate, parts 1 to 3, the Chartered Insurance Institute | 1996 |
| Wills and Estate Planning Certificate | 2024 |
| Later Life Lending Advice Standard, Society of Later Life Advisers (SOLLA) | Current |
How did I end up advising only on equity release?
I started in financial services in 1996 and moved into mortgages in 1999. I qualified in equity release in 2009 and set up my own firm, Pellucid, the following year, and for more than a decade equity release sat alongside ordinary mortgages.
That changed when I reached the age where I could take out a lifetime mortgage myself. I gave up ordinary mortgages and have advised only on later-life lending since. My colleagues at Pellucid look after mortgages and insurance, and Trusted Equity Release is the later-life side of the firm.
Why do I handle wills and lasting powers of attorney too?
Because the families I help kept needing them at the same time. So in 2024 I sat and passed the Wills and Estate Planning Certificate. When Eileen Lack reviewed me that March, the one job left on the file was finishing the LPAs.
How do I work?
It's me from start to finish: the first call, the visit, the recommendation and the paperwork, with no call centre or administrator in between.
- I come to you. I'm happy with a good hour's drive from March, which covers Cambridgeshire, Norfolk, Suffolk, south Lincolnshire and Northamptonshire.
- Or we talk on the phone. Video calls are rare, for a reason I understand: "if it's not done face to face, the vast majority just want a phone call, because they're in the same boat as me."
- Family are welcome, in the room or on the line. For one gran buying a new home, I set up the first meeting with her and her daughter and brought her grandson in by phone from another county.
- Every recommendation comes with a letter explaining it in plain English. If equity release isn't right for you, I'll say so, and why.
- I'll point you to a specialist equity release solicitor. Your solicitor acts for you, not for me, and should know these plans well.
How am I paid?
Your first conversation costs nothing and commits you to nothing. There's nothing to pay unless your plan completes. If it does, my fee is a fixed fee, not a percentage of what you release, and you can pay it directly or have it taken from the plan. I'll tell you the figure on the phone, with the solicitor's cost, before you decide anything.
It's also a lifetime fee. If you've got 15 years in front of you, call me up and I'll help you for nothing.
What do my clients say?
Six people have reviewed me on Google, all five stars. Three of them, in their own words:
“Many companies take advantage of the elderly, but this was clearly not the case with Jeremy. He thoroughly explained all options and even assisted my gran with completing complex application forms.”
“Had the pleasure of dealing with Jeremy on behalf of my mum for equity release on her home. If you want someone you can genuinely trust then don't go anywhere else! Jeremy is probably the most honest and genuine advisor that you will come across.”
“Jeremy was very professional throughout the process, kept us uptaded at all times, nothing was too much trouble.”
Read every review, with my replies, or see them on Google.
Who am I away from work?
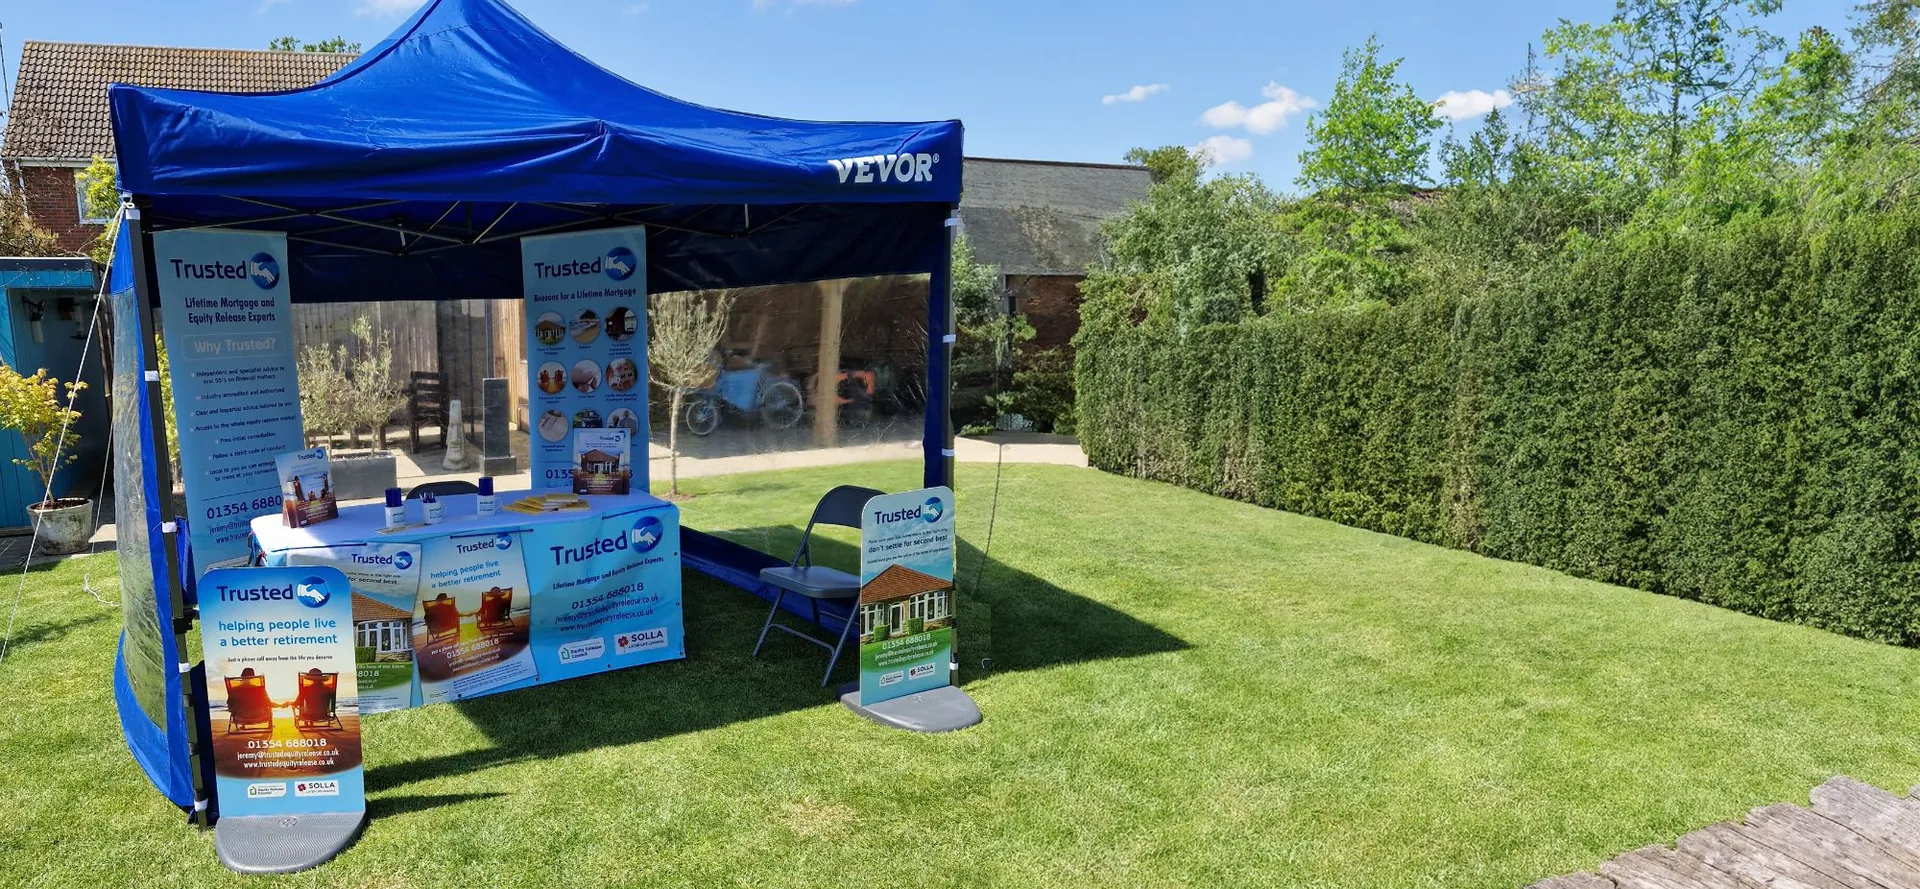
My three miniature dachshunds, Mr Bojangles, Amber and Malteser, take up most of it. The rest goes on golf at the weekend, watching my local village football team, the occasional day on the allotment, and my godsons and family friends. You may also have seen my blue gazebo at a local show.
FAQ
Are you independent?
Do you only do equity release?
Can my family be there?
What if equity release isn't right for me?
Book your free initial consultation today.
Pick up the phone and speak to Jeremy directly. If equity release is not the right choice, I will say so.
07768 972861 Or try the quick calculator