Home › Equity release › Companies to avoid
Reviewed September 2026Equity release companies to avoid
If you're searching for equity release companies to avoid, you're in the right place, and your instinct is healthy. I have advised on later-life lending since 2009, and the firms worth avoiding are rarely famous names: they are firms with a pattern. This page gives you the pattern, and a three-minute check that works on any company in the country.
- Member of the Equity Release Council
- SOLLA Later Life Lending Advice Standard
- Authorised and regulated by the FCA, FRN 981845
Quick answer: which equity release companies should you avoid?
Avoid any firm operating outside Equity Release Council standards, any plan without the no negative equity guarantee, and anyone rushing you towards a deadline. The name on the letterhead matters far less than those three checks, and all three are verifiable before you speak to anyone.
Why listen to me on this?
Because I see every provider's paperwork. I am an independent, whole-of-market adviser, a member of the Equity Release Council, and I hold the SOLLA Later Life Lending Advice Standard. Trusted Equity Release is a trading name of Pellucid Ltd, authorised and regulated by the Financial Conduct Authority, FRN 981845. And as it says on my homepage: if equity release is not the right choice, I will say this.
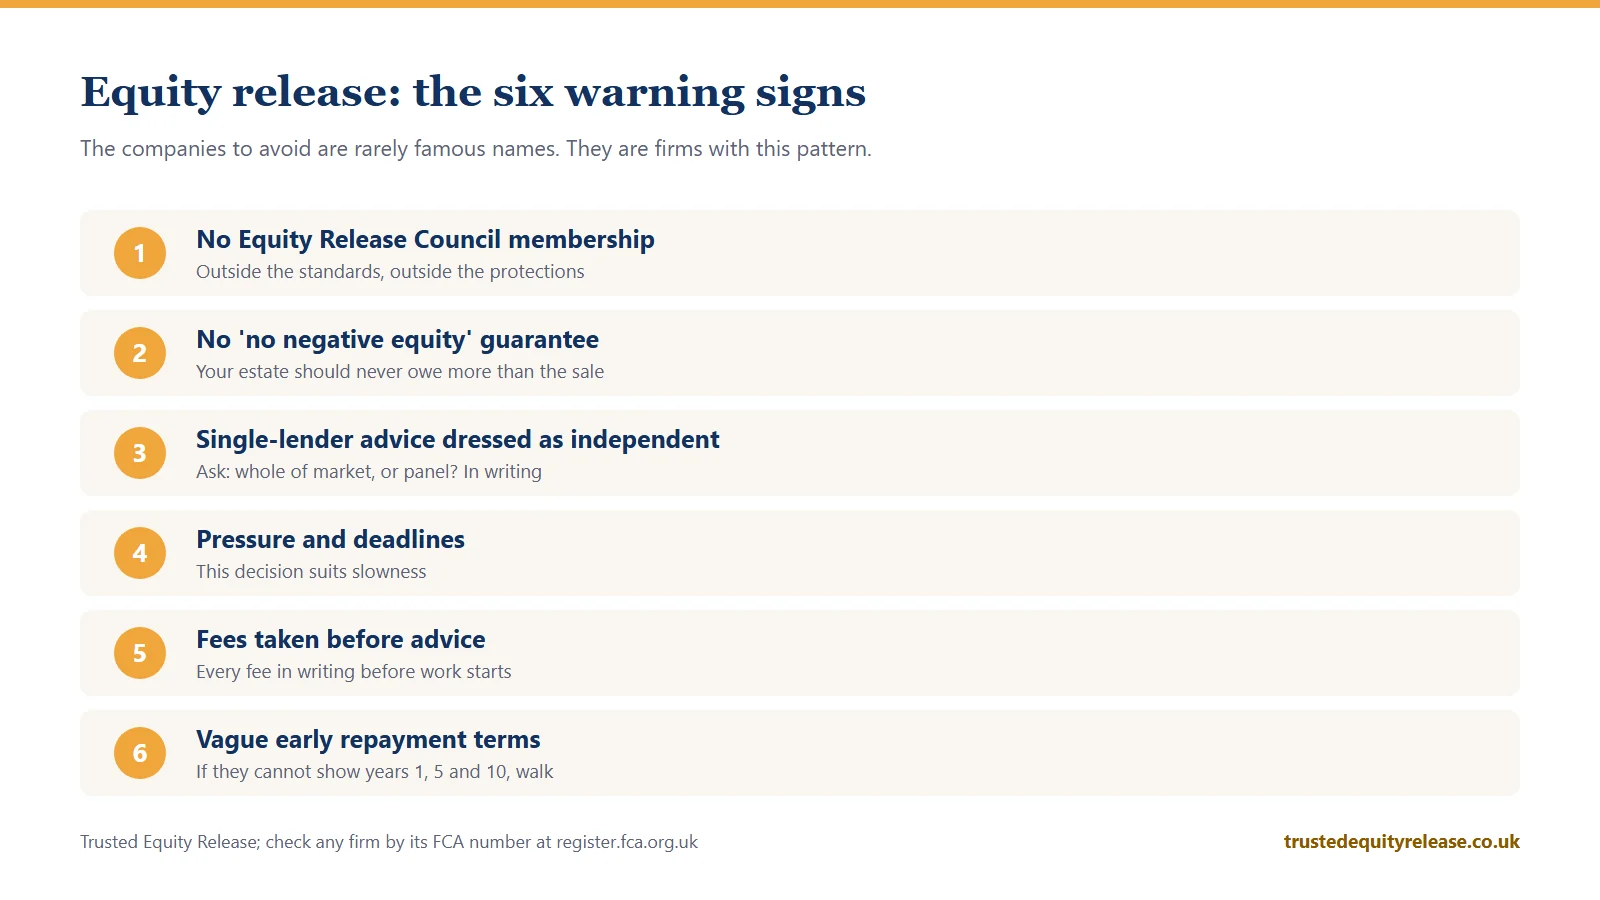
The six warning signs
No Equity Release Council membership
Council plans must carry the product standards, including the right to stay in your home for life and penalty-free partial repayments. A firm outside the Council is asking you to give those protections up. Ask why.
No "no negative equity guarantee"
The guarantee means that when the property is sold, neither you nor your estate can owe more than it fetches. Every Council plan has it. Any equity release loan without it belongs to the era this market spent twenty years living down.
Single-lender "advice" dressed up as independent
Some firms can only recommend one lender's plans, which is fine when it is stated and dangerous when it is dressed as a market comparison. Ask one question: "whole of market, or panel?" and get the answer in writing.
Pressure and deadlines
Rate-expiry countdowns, tonight-only offers, discouraging you from talking to family. Equity release is a decision that suits slowness. One of my clients paused her application partway through, had a long think, and finished it months later when she was sure. That is how the process should treat you.
Fees taken before advice
Reputable firms tell you every fee in writing before work starts, and charge for work done, not for promises. Money requested up front to "secure a rate" or "reserve funds" is a leaving signal.
Vague early repayment terms
If a firm cannot show you, in writing and in plain numbers, what leaving the plan early would cost in years one, five and ten, the vagueness is the answer.
How to check any company in three minutes
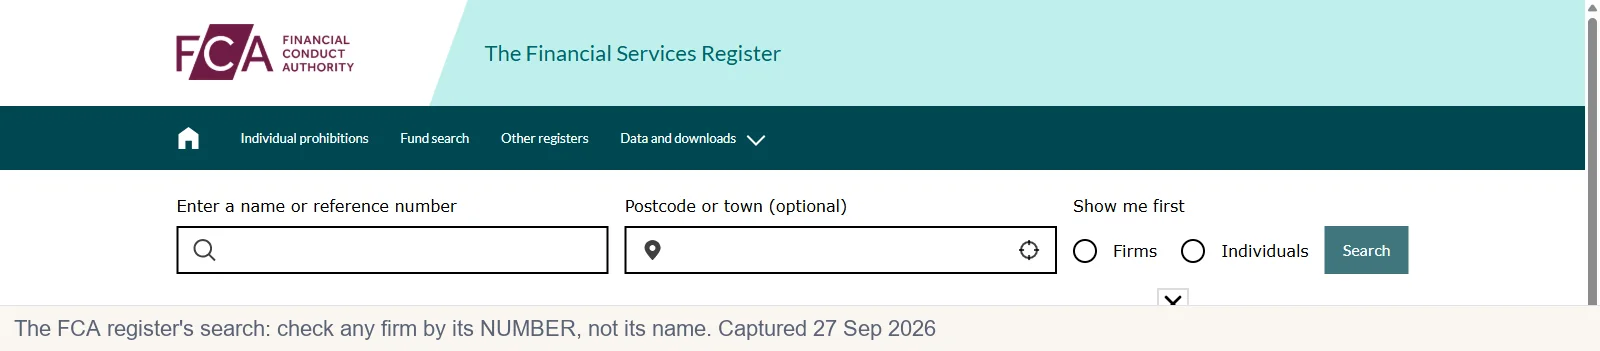
Search the Financial Conduct Authority (FCA) register, and search by the NUMBER, not the name. Here is why, from my own register entry. My company is Pellucid Ltd, FRN 981845, authorised. There is also a DISSOLVED firm on the register called Pellucid Ltd, an unconnected earlier company with a different number, no longer authorised, from the same part of the country. Search by name alone and you could land on the dead record and conclude the wrong thing entirely, in either direction.
The three lines to read
Take the firm's FCA number from their website footer and put the NUMBER into register.fca.org.uk. Then read three lines: the status says "Authorised", the permissions cover mortgage or home-finance advice, and the trading names include the brand you are actually talking to. Three minutes, and it filters more bad actors than any review site.
What about the big household names?
The famous brands in this market are Council members, and the lenders on my own panel all operate inside the standards. The realistic risk in 2026 is rarely the brand on the plan: it is the process around you, which is what the six signs above test. For the positive version of this page, how to choose WELL between the legitimate companies, see best equity release companies.
Why do people say equity release is bad?
Two reasons, one current and one historical. The current one is compound interest: the interest rate is fixed for life, but make no repayments on the lump sum you release and the debt grows, which is real, disclosed, and shown to you in a personalised illustration before you sign. It is also why for every £1 released each year, over-55s hold £852 of housing wealth, most people, sensibly, take their time; the numbers are in my equity release statistics. The historical reason is the pre-standards era, whose worst products are precisely what the Council rules and the signs on this page exist to keep you away from.
Is there a better alternative for you?
Sometimes, and a real adviser says so before recommending anything. Downsizing, a retirement interest-only mortgage, family help or spending savings first can each beat a lifetime mortgage, and I have had cases where the honest answer was a bridging loan and a referral to another firm. The options are laid out on alternatives to equity release.
FAQ
Who is the best equity release provider?
Are all equity release companies FCA regulated?
What should you do if you think you were mis-sold?
Book your free initial consultation today.
Pick up the phone and speak to Jeremy directly. If equity release is not the right choice, I will say so.
07768 972861 Or try the quick calculator