Home › Equity release › Best equity release companies › Aviva review
Product facts checked 27 September 2026Aviva equity release: an independent review
If you're researching Aviva equity release, you're in the right place, and probably further along than you think: most people who ask me about Aviva have half-decided already. This review is written by an independent adviser who places cases with Aviva and with its competitors, which is the one perspective Aviva's own pages cannot offer.
- Member of the Equity Release Council
- SOLLA Later Life Lending Advice Standard
- Authorised and regulated by the FCA, FRN 981845
Quick answer: is Aviva good for equity release?
Aviva is one of the UK's largest lifetime mortgage lenders and an Equity Release Council member, with genuinely strong repayment flexibility and downsizing protection. Whether it is right for YOU depends on your age, property and plans, which is a whole-of-market question, not an Aviva question.
Why read an Aviva review from an independent adviser?
Because advice is mandatory on every equity release plan under FCA rules, so the real decision is never "Aviva or nothing", it is "Aviva or one of nine other lenders", and only a whole-of-market equity release adviser runs that comparison honestly. Whoever you choose, remember the constant: a lifetime mortgage is secured against your home and will reduce the value of your estate. I am a member of the Equity Release Council, a later-life lending specialist since 2009, and Trusted Equity Release is a trading name of Pellucid Ltd, authorised and regulated by the Financial Conduct Authority, FRN 981845. A conversation, or a second opinion on a quote you already hold, costs you nothing.
What does Aviva's equity release actually offer?
From Aviva's own published pages, checked 27 September 2026:
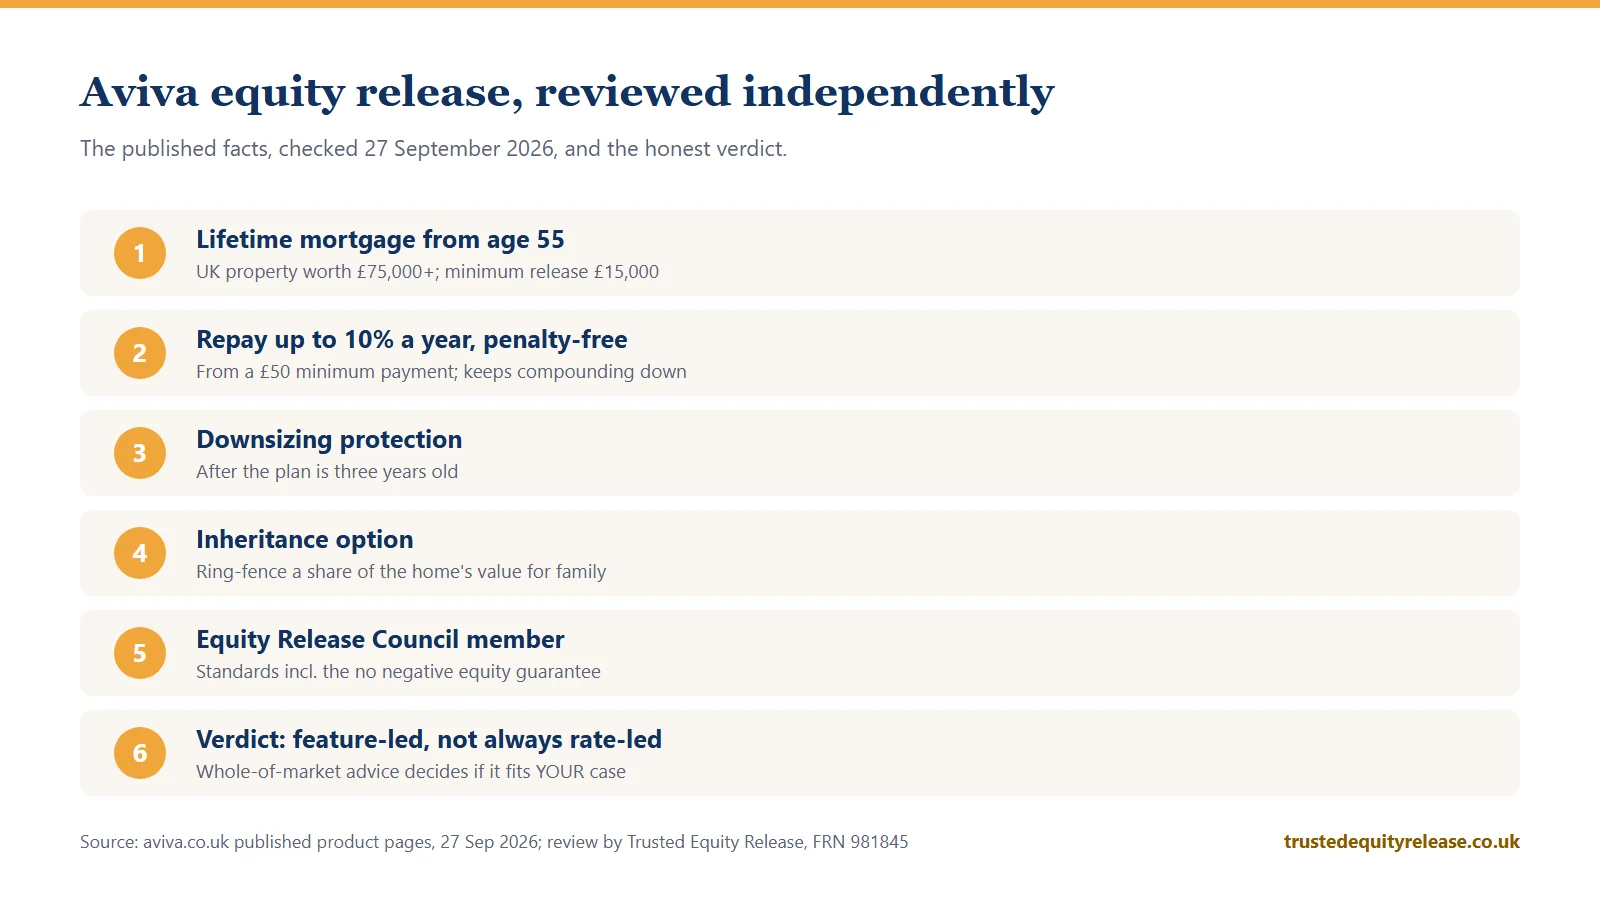
- A lifetime mortgage for UK homeowners aged 55 or over, on properties worth at least £75,000, with a minimum release of £15,000.
- Penalty-free partial repayments of up to 10% of the amount borrowed each year, from a £50 minimum payment, which is generous flexibility for keeping the compounding down.
- Downsizing protection once the plan is three years old, so a future move does not have to mean an early repayment charge.
- An inheritance option: you can ring-fence a percentage of the home's value for family, in exchange for borrowing less.
- Equity Release Council membership, carrying the standards and the no negative equity guarantee.
Those are the headline mechanics. The plan-level details move, which is what a personalised illustration is for.
What is Aviva's equity release interest rate?
Aviva prices each case individually, so there is no single "Aviva rate": the offer depends on age, property and loan size, and can change with health disclosures. For orientation, advertised lifetime mortgage rates across the market run from about 6.25% MER upwards in September 2026, and my equity release interest rates page tracks the picture monthly. The rate on your illustration is the only number worth planning around.
How long does Aviva equity release take?
The same stages as any lifetime mortgage: advice and recommendation, application, the property valuation, the offer, your independent solicitor's work, then completion. Weeks rather than days, with the legal stage usually setting the pace, and it moves fastest when the paperwork is ready before the application goes in. Deadlines should never be driving this anyway; a process that respects a pause is a feature, not a delay.
When is Aviva not the right choice?
When the case is rate-led rather than feature-led. Aviva's strengths are the flexible repayments, the downsizing protection and the inheritance option; you pay for strengths like those through the pricing. A borrower who wants the smallest possible roll-up on a straightforward case, or whose health opens up enhanced terms at a specialist lender, can find a sharper offer elsewhere on the day. That is not a criticism of Aviva. It is the reason the comparison exists, and how I judge all the companies is its own page.
Already holding an Aviva quote? Get a second opinion for nothing
This is the most useful thing I do on Aviva cases. Bring me the illustration you have been given and I will put it against the whole market in one conversation: the rate, the drawdown terms, the repayment flexibility, and whether a health disclosure would change either. No charge for that, and no awkwardness either way. Sometimes the answer is "Aviva is exactly right, proceed with confidence", and clients tell me that sentence alone was worth the call.
Half my job is stopping people paying more than they need to; the other half is stopping second thoughts from ruining a good deal. Email me, request a printed brochure, or get in touch on the number at the top of this page.
How I run the comparison
- Your numbers first. Age, property, what the money is for, and whether income could support any repayments.
- The whole market against Aviva. Every lender's live terms on your case, not last month's table.
- Health and lifestyle disclosures. The step people skip; it can reprice everything.
- A written recommendation. Aviva if Aviva wins, another lender if not, and neither if the honest answer is "not yet". Then a personalised illustration before anything is decided.
FAQ
Is Aviva a member of the Equity Release Council?
What are Aviva's minimum age and property value?
Can you make repayments on an Aviva lifetime mortgage?
Sources
- Aviva: equity release (all product facts, checked 27 Sep 2026)
- Equity Release Council: standards
- MoneyHelper: equity release
- FCA register: Pellucid Ltd, FRN 981845
Book your free initial consultation today.
Pick up the phone and speak to Jeremy directly. If equity release is not the right choice, I will say so.
07768 972861 Or try the quick calculator